A BSCIC loan for business in Bangladesh is a direct, low-interest government financing facility offered by the Bangladesh Small and Cottage Industries Corporation (BSCIC) to cottage, micro, small, and eligible medium industrial entrepreneurs. Under BSCIC’s active direct loan programs, eligible entrepreneurs can borrow between BDT 50,000 and BDT 20 lakh at 5% annual interest for women and 6% for men, with repayment periods ranging from 1 to 5 years. Up to BDT 2 lakh is collateral-free, requiring only one personal guarantor, and applicants can apply directly at any of Bangladesh’s 64 BSCIC district offices without going through a commercial bank.
Commercial bank SME loans in Bangladesh often carry interest rates between 12% and 15%, strict collateral requirements, and lengthy approval cycles that shut out smaller workshops and first-time factory owners. BSCIC’s revolving loan funds address that exact financing gap. If you run a light manufacturing unit, agro-processing facility, handicrafts workshop, tailoring house, or beekeeping enterprise, knowing how BSCIC’s direct loan funds work can save your business lakhs of taka in borrowing costs.
This guide explains BSCIC’s three active loan schemes, current interest rates, approval tiers across district, regional, and head offices, equity and collateral rules, required documents, realistic repayment math, and how BSCIC compares with commercial bank SME loans and Bangladesh Bank refinance schemes.
What Is a BSCIC Loan for Business?
The Bangladesh Small and Cottage Industries Corporation (BSCIC) operates under the Ministry of Industries to develop cottage, micro, small, and medium enterprises (CMSMEs) across Bangladesh. Many business owners know BSCIC primarily for allocating industrial plots inside BSCIC Industrial Estates and offering entrepreneurship training through the Small and Cottage Industries Training Institute (SCITI). Fewer realize that BSCIC also runs direct revolving loan funds from its own district network.
Unlike commercial bank refinance programs—where a government agency channels funds through private or state-owned banks—BSCIC’s direct loan programs are processed, verified, sanctioned, and disbursed directly by BSCIC offices. You do not need to open a commercial loan file at a private bank or pay bank-level processing markups to access these three funds. When collateral is required for amounts above BDT 2 lakh, the mortgage documentation is handled directly with BSCIC and returned to the entrepreneur once the loan is repaid in full.
In November 2026, BSCIC inaugurated a nationwide disbursement of BDT 14.03 crore to 511 entrepreneurs in a single drive, reporting a loan recovery rate above 90%. During that announcement, the Ministry of Industries also signaled that the government is reviewing an expansion of both the BDT 2 lakh collateral-free limit and district-level sanction authority. Until an official circular revises those ceilings, however, applicants must plan around the current published limits outlined below.
The Three Active BSCIC Business Loan Programs
BSCIC currently operates three distinct direct loan programs, as confirmed by BSCIC’s FY 2026–27 revolving fund target notices and reporting in Prothom Alo (September 2026). While each fund was created for a specific purpose, BSCIC applies the same core interest rates and application rules across all three.
| BSCIC Loan Program | Launch Year | Current Fund Size (2026) | Entrepreneurs Served | Loan Limit |
|---|---|---|---|---|
| Stimulus Package Refinance Loan Program | FY 2020–21 | BDT 270 crore | 9,291+ | BDT 50,000 – BDT 20 lakh |
| BINIT (BSCIC Own Fund Loan Program) | FY 2015–16 | BDT 150 crore | 8,873+ | BDT 50,000 – BDT 20 lakh |
| Beekeeping (Apiculture) Loan Program | 2019 | BDT 4.78 crore | 1,497+ | Up to BDT 50,000 |
1. Stimulus Package Refinance Loan Program
Launched in FY 2020–21 with an initial allocation of BDT 100 crore to help cottage and small enterprises recover from the pandemic, this fund was later converted into a permanent revolving refinance pool. By June 2026, the fund had grown to BDT 270 crore and financed more than 9,291 entrepreneurs. It serves working capital, machinery purchase, and production expansion needs for small and cottage enterprises.
2. BINIT (BSCIC Own Fund Loan Program)
BINIT—short for BSCIC Nijoswo Tohobil (BSCIC Own Fund)—began in FY 2015–16 with BDT 15 crore and has expanded tenfold to BDT 150 crore, supporting over 8,873 entrepreneurs. Official rules and operating manuals for this program are published on the BSCIC BINIT Loan Program page. BINIT is the primary evergreen channel for small manufacturers, cottage producers, and BSCIC-trained entrepreneurs seeking affordable expansion capital.
3. Marginal Beekeepers (Apiculture) Loan Program
Started in 2019 for marginal honey producers, this specialized BDT 4.78 crore revolving fund offers small working-capital loans up to BDT 50,000 per entrepreneur. More than 1,497 beekeepers have received funding under this program to buy bee boxes, extraction tools, and seasonal migration supplies. Applicants trained in beekeeping by BSCIC receive priority consideration.
BSCIC Business Loan Interest Rates, Limits, and Approval Tiers
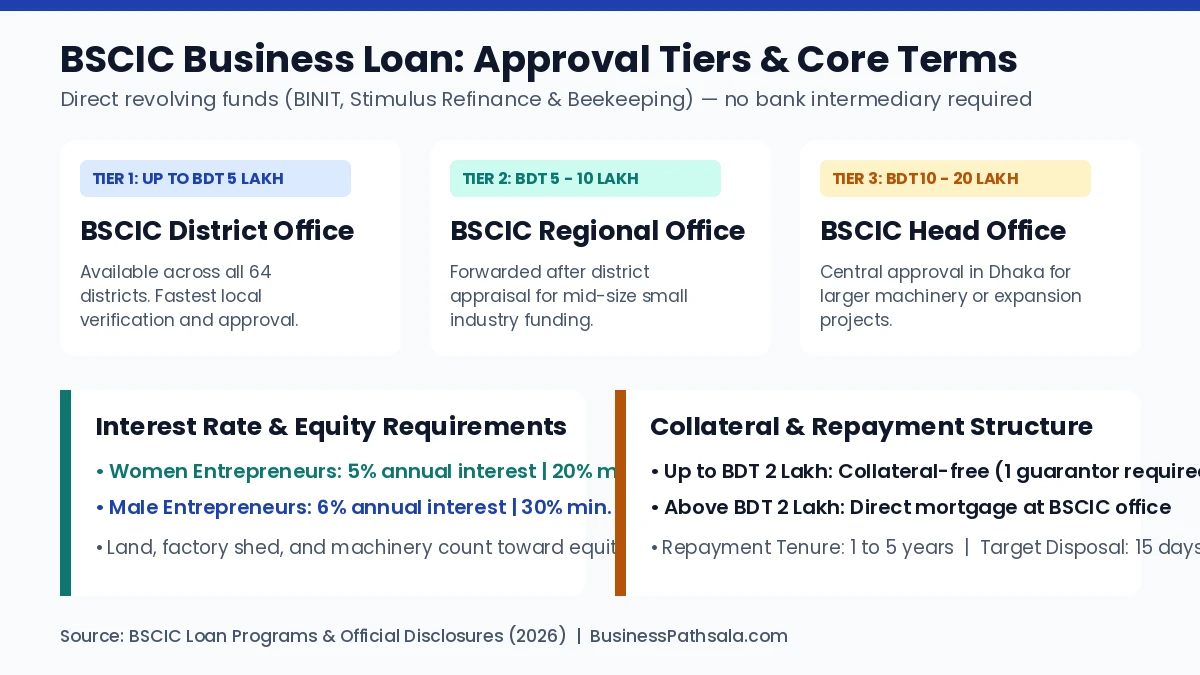
BSCIC charges 5% annual interest for women entrepreneurs and 6% annual interest for male entrepreneurs across its direct loan programs, with loan amounts ranging from BDT 50,000 to BDT 20 lakh and repayment tenures between 1 and 5 years. Approval authority depends on the loan size you request, which directly affects how quickly your file moves.
| Loan Feature | Current BSCIC Direct Loan Terms (2026) |
|---|---|
| Minimum & Maximum Amount | BDT 50,000 to BDT 20,00,000 (Beekeeping: up to BDT 50,000) |
| Interest Rate (Women Entrepreneurs) | 5% per annum |
| Interest Rate (Male Entrepreneurs) | 6% per annum |
| Collateral-Free Limit | Up to BDT 2,00,000 (one personal guarantor required) |
| Collateral Above BDT 2 Lakh | Mortgage/security processed directly at the BSCIC office |
| Minimum Equity (Women) | 20% of total project cost |
| Minimum Equity (General / Male) | 30% of total project cost |
| Repayment Tenure | 1 to 5 years |
| Standard Disposal Timeline | 15 working days from complete application submission (target rule) |
How Tiered Approval Works
Every entrepreneur submits their initial application at the BSCIC District Office covering their business location, regardless of the loan size. After preliminary scrutiny and field verification, the sanctioning authority is determined by three tiers:
- Up to BDT 5 lakh: Approved directly by the BSCIC District Office. Because the file stays local, this tier typically clears fastest.
- Above BDT 5 lakh to BDT 10 lakh: Recommended by the District Office and approved by the BSCIC Regional Office.
- Above BDT 10 lakh to BDT 20 lakh: Forwarded through regional channels for final approval by the BSCIC Head Office in Dhaka.
What Counts Toward Your 20%–30% Equity Requirement?
New applicants often worry that a 30% equity requirement (or 20% for women entrepreneurs) means holding that exact sum in cash inside a bank account. Under BSCIC rules, your existing business assets count toward equity. Owned land, factory sheds, workshop structures, installed machinery, and related fixed industrial investments can all be calculated as part of your equity contribution. Keeping purchase invoices, land deeds, or valuation records ready helps the inspecting officer verify your equity share quickly.
Who Is Eligible for a BSCIC Business Loan?
Any Bangladeshi citizen aged 18 to 65 with a clean credit record who operates a sole proprietorship or partnership in an industry listed under the National Industrial Policy 2022 can apply for a BSCIC business loan.
Mandatory Eligibility Criteria
- Citizenship and Age: Must be a Bangladeshi citizen between 18 and 65 years old at the time of application.
- Residency or Business Location: Must be a permanent resident of the district where you apply, or operate an established enterprise in an inter-district location verified by BSCIC.
- Clean Credit History: You cannot be a loan defaulter at any commercial bank or non-bank financial institution. A clean Credit Information Bureau (CIB) record is required.
- Legal Business Structure: Both sole proprietorships and registered partnerships are eligible.
- Approved Sector: The business must fall within the industrial and productive sectors recognized in the National Industrial Policy 2022 (such as light engineering, food and agro-processing, garments and boutiques, leather goods, packaging, plastics, furniture, handicrafts, ICT hardware assembly, or beekeeping). Pure speculative trading without value addition is generally outside BSCIC’s industrial mandate.
Priority Applicant Categories
Because BSCIC revolving funds operate with annual district-level disbursement targets, offices prioritize applicants who align closely with national industrial and employment goals. You gain an advantage if you fall into one of these groups:
- Women entrepreneurs running manufacturing, handicraft, food-processing, or service-linked small industries.
- New entrepreneurs launching viable first-time productive ventures.
- BSCIC Industrial Estate plot holders who need working capital or machinery financing to start or expand production. (If you are still applying for a plot, see our guide on writing a BSCIC project profile for an industrial plot.)
- Export-oriented small industries producing goods for overseas buyers or local export linkages.
- BSCIC-trained unemployed youth and women who hold training certificates from BSCIC District Offices, the BSCIC Training Institute (SCITI), Skill Development Training Centres, the BSCIC Design Centre, or BSCIC apiculture courses.
What Can You Use a BSCIC Business Loan For?
BSCIC officers review your stated loan purpose during verification and disburse funds strictly for productive business activities rather than personal consumption. Common approved uses include:
- Machinery and Equipment Purchase: Buying sewing machines, packaging units, oil expellers, woodworking tools, bakery ovens, or light engineering equipment.
- Working Capital: Purchasing raw materials, bulk inputs, packaging supplies, and covering short-term production cycles.
- Workshop Upgrading: Modest renovations, utility connections, or safety upgrades needed to increase output.
- Product Marketing and Distribution: Funding packaging improvements, trade fair participation, or local distribution expansion tied to production growth.
If your enterprise is primarily a traditional rural or home-based craft unit, you may also want to compare BSCIC’s direct loans with other cottage industry loan schemes in Bangladesh before choosing a financing path.
Documents Required for a BSCIC Business Loan Application
BSCIC publishes separate official forms for Small Industry Loans, Cottage Industry Loans, and Beekeeping Development Loans on its BSCIC Loan Application Forms portal. Exact supporting papers can vary slightly depending on whether you request a collateral-free loan (up to BDT 2 lakh) or a secured loan (above BDT 2 lakh). Confirm the final checklist with your district office, and prepare the following core file:
| Document Category | Typical Papers to Prepare |
|---|---|
| Official Application Form | Completed BSCIC loan form (Small, Cottage, or Beekeeping) with passport-size photographs of the applicant. |
| Identity & Residency | National Identity Card (NID) copy and citizenship/permanent residency certificate from the Union Parishad, Pourashava, or City Corporation. |
| Business Legal Papers | Updated Trade License; BSCIC industrial registration certificate (if registered); registered Partnership Deed (for partnerships); e-TIN certificate (where applicable). |
| Premises & Utility Proof | Ownership deed or valid workshop/factory rent agreement, plus recent electricity or utility bill. |
| Project & Financial Plan | Short project profile or business plan showing proposed machinery quotations, raw material costs, monthly sales, and repayment capacity; bank statement (if maintaining a business account). |
| Guarantor Papers (Up to BDT 2 Lakh) | NID, photograph, income/solvency proof, and signed guarantee consent from one acceptable personal guarantor. |
| Collateral Papers (Above BDT 2 Lakh) | Original land/property ownership deeds, updated mutation (Namjari) khatian, DCR, current land tax (Khajna) receipt, and 12-year non-encumbrance certificate (NEC), as required by BSCIC’s legal verification. |
| Training Certificate (If Applicable) | Certificate from BSCIC District Office, SCITI, BSCIC Design Centre, or apiculture training to claim priority status. |
For loans above BDT 5 lakh—especially when applying for machinery or factory expansion—a clear financial projection makes a major difference during committee review. Our guide on preparing an SME loan project profile in Bangladesh shows how to structure cost estimates and cash-flow tables so reviewers can verify your repayment ability without guesswork.
How to Apply for a BSCIC Business Loan Step by Step
To apply for a BSCIC business loan, visit the BSCIC District Office in your district with your business documents, submit the official loan application form, complete a site and purpose verification by BSCIC officers, and await tiered committee approval. Applications are accepted year-round—you do not need to wait for a special annual deadline, although disbursement depends on the district’s available revolving fund allocation.
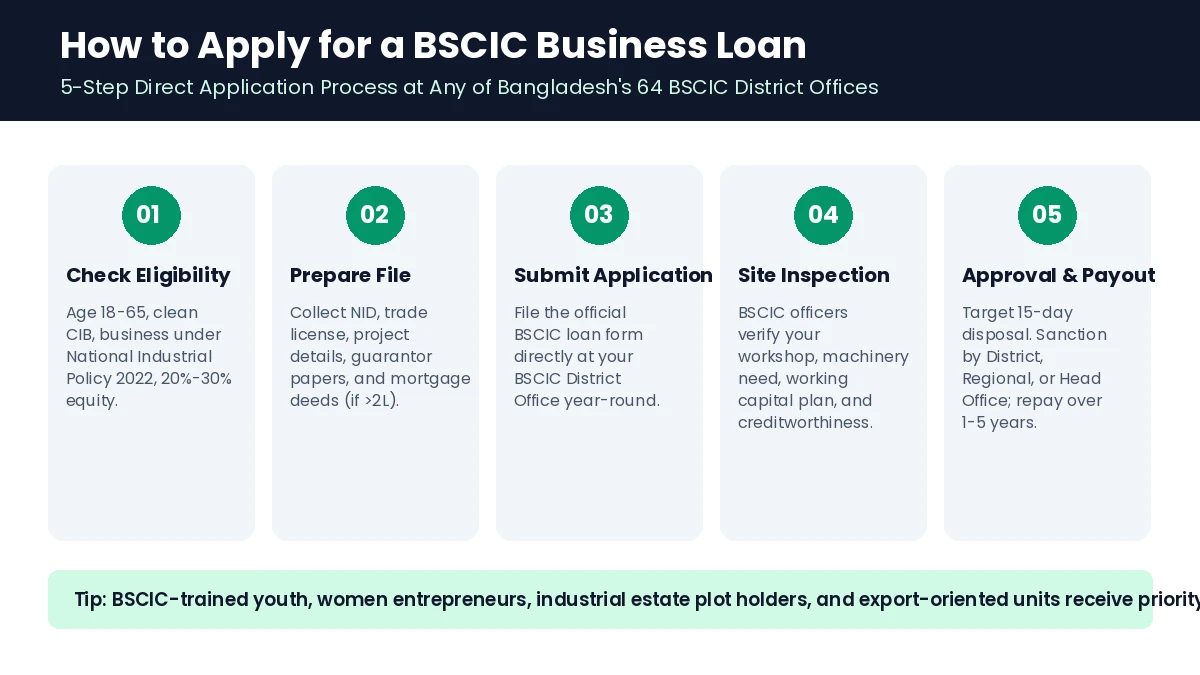
- Confirm Eligibility and Pick Your Loan Tier: Verify your age (18–65), clean CIB status, and sector eligibility under the National Industrial Policy 2022. Decide whether a collateral-free loan up to BDT 2 lakh meets your immediate need or whether you need a larger secured loan up to BDT 20 lakh.
- Collect Forms and Confirm Local Requirements: Visit your local BSCIC District Office (available in all 64 districts) or download the relevant form from the official BSCIC portal. Ask the loan officer about current fund availability and confirm the exact document checklist for your requested amount.
- Assemble Your Application File: Gather your NID, updated trade license, premises proof, machinery supplier quotations, equity proof, and guarantor or collateral documents. Ensure your stated loan amount matches your machinery quote or working-capital calculation.
- Submit Directly and Undergo Field Inspection: File the complete application at the BSCIC District Office. A BSCIC officer will verify your identity, credit status, business location, existing machinery, and stated purpose (machinery purchase, working capital, or marketing).
- Committee Approval, Documentation, and Disbursement: Under BSCIC rules, complete applications are targeted for disposal within 15 days. Loans up to BDT 5 lakh are sanctioned locally; larger files move to the Regional Office (BDT 5–10 lakh) or Head Office (BDT 10–20 lakh). Once approved, you sign the loan agreement (and complete mortgage formalities if above BDT 2 lakh) and receive disbursement.
Real Cost Comparison: BSCIC Loan vs. Commercial Bank SME Loan
Interest rate percentages look abstract until you translate them into monthly cash flow. To illustrate the real savings of a BSCIC business loan, consider an entrepreneur borrowing BDT 5,00,000 for 3 years (36 months) using a standard reducing-balance amortization calculation (illustrative example; actual installment schedules depend on the lender’s exact compounding and grace-period terms):
| Financing Option (Illustrative BDT 5 Lakh, 3 Years) | Annual Interest Rate | Approx. Monthly Installment | Approx. Total Interest Paid | Interest Saved vs. 14% Bank Loan |
|---|---|---|---|---|
| BSCIC Direct Loan (Women Entrepreneur) | 5.0% | BDT 14,985 | BDT 39,476 | BDT 75,896 saved |
| BSCIC Direct Loan (Male Entrepreneur) | 6.0% | BDT 15,211 | BDT 47,595 | BDT 67,777 saved |
| Commercial Bank SME Loan (Typical Market Rate) | 14.0% | BDT 17,089 | BDT 1,15,372 | Baseline |
On a BDT 5 lakh loan over three years, a woman entrepreneur borrowing from BSCIC at 5% pays roughly BDT 75,900 less in interest than she would on a 14% commercial bank loan. On a BDT 15 lakh machinery loan over five years, that gap widens into lakhs of taka that remain inside the business as working capital. To compare current commercial bank rates across Bangladesh, review our updated breakdown of SME loan interest rates in Bangladesh.
BSCIC Direct Loan vs. Bangladesh Bank & SME Foundation Schemes
BSCIC is not the only low-interest institutional option for Bangladeshi small businesses. Depending on how much capital you need and whether you are willing to work through a bank, two other public-backed channels may fit better—especially if your financing need exceeds BDT 20 lakh.
| Feature | BSCIC Direct Loan | Bangladesh Bank Small Enterprise / New Entrepreneur Refinance | SME Foundation Credit Wholesaling |
|---|---|---|---|
| Where You Apply | Directly at 64 BSCIC District Offices | Participating commercial banks and NBFIs | Partner banks and NBFIs |
| Loan Limit | BDT 50,000 – BDT 20 lakh | Cottage up to BDT 5L; Micro up to BDT 20L; Small up to BDT 50L (New Entrepreneurs: up to BDT 10L collateral-free / BDT 25L secured) | Typically BDT 1 lakh – BDT 25 lakh (cluster/sector dependent) |
| Interest Rate | 5% (Women) / 6% (Men) | Varies by scheme (e.g., max 5%–7% under specific CMSME refinance windows) | Subsidized single-digit rates set per cycle (often 6%) |
| Collateral-Free Limit | Up to BDT 2 lakh | Up to BDT 10 lakh (New Entrepreneur scheme) or up to BDT 25 lakh for women under bank policies | Varies by partner bank policy |
| Best Fit For | Small manufacturers, cottage units, BSCIC trainees wanting direct, bank-free low-cost loans | Larger small industries needing BDT 20 lakh to BDT 50 lakh+ via a bank | Cluster-based SMEs and women entrepreneurs applying through partner banks |
You can verify current central bank refinance caps and participating institutions directly on the Bangladesh Bank SMESPD Schemes portal. If your business operates in a recognized SME cluster, check our guide on the SME Foundation Credit Wholesaling Program. And if you are scaling a larger manufacturing plant that requires more than BDT 20 lakh, explore our overview of loans for small factories in Bangladesh.
Common Mistakes and Practical Limitations to Know Before Applying
A 5%–6% direct government loan sounds straightforward on paper, yet many applications stall or get rejected for avoidable reasons. Knowing the real bottlenecks upfront saves weeks of back-and-forth.
- Limited Annual District Allocations: BSCIC’s revolving funds (BDT 270 crore stimulus pool and BDT 150 crore BINIT pool) serve all 64 districts. If your district office has already committed its quarterly or annual target, new approvals may wait until repayments replenish the revolving pool. Ask about local fund availability before paying for land valuation or legal extracts.
- Applying for Pure Retail Trading: BSCIC’s mandate covers industrial, cottage, and productive enterprises aligned with the National Industrial Policy 2022. A conventional grocery shop or general trading store without manufacturing, processing, or craft value addition is usually better suited for a commercial bank SME loan.
- Weak Purpose Documentation: Stating “business expansion” without supplier quotations for machinery or a breakdown of raw-material cycles weakens your file. Attach concrete vendor quotes and a simple monthly revenue-and-expense projection.
- Incomplete Land/Mortgage Papers (Above BDT 2 Lakh): Missing mutation (Namjari) records, unpaid land tax receipts, or broken ownership chains are the single biggest cause of delay on secured loans in Bangladesh. Verify your property papers before requesting more than BDT 2 lakh.
- Overlooking Credit History (CIB): Even a small unresolved credit card default or old agricultural loan arrears can disqualify an otherwise strong workshop. Clear any overdue obligations before applying.
Frequently Asked Questions About BSCIC Business Loans
Can I get a BSCIC loan for business without collateral?
Yes. Under current BSCIC rules, loans up to BDT 2 lakh are collateral-free and require only one acceptable personal guarantor. Loans above BDT 2 lakh require collateral/mortgage processed directly through the BSCIC office.
What is the maximum BSCIC business loan amount in Bangladesh?
Entrepreneurs can borrow between BDT 50,000 and BDT 20 lakh under BSCIC’s direct revolving loan programs (BINIT and the Stimulus Package Refinance fund). Marginal beekeepers under the specialized apiculture scheme can borrow up to BDT 50,000.
What is the interest rate on a BSCIC business loan?
BSCIC charges 5% annual interest for women entrepreneurs and 6% annual interest for male entrepreneurs across its direct loan programs.
Do I need to apply through a bank for a BSCIC loan?
No. For BSCIC’s direct loan schemes (BINIT, Stimulus Refinance, and Beekeeping), you apply directly at any of the 64 BSCIC District Offices. You do not need to go through a commercial bank or NBFI.
How long does BSCIC loan approval take?
BSCIC’s standard operating rule sets a target of 15 days to dispose of a complete loan application. In practice, applications up to BDT 5 lakh approved at the District Office move fastest, while files above BDT 5 lakh that require Regional or Head Office approval—or legal mortgage verification—can take longer.
Can a new entrepreneur without an existing factory apply?
Yes. New entrepreneurs are explicitly listed as a priority category, especially unemployed youth and women who have completed training through BSCIC District Offices, SCITI, Skill Development Training Centres, or the BSCIC Design Centre. You still need to meet the minimum equity rule (20% for women, 30% for men) and present a viable project plan.
Final Thoughts
A BSCIC loan for business is one of the most affordable formal financing options available to small manufacturers, cottage producers, agro-processors, and trained new entrepreneurs in Bangladesh. With 5% interest for women, 6% for men, up to BDT 2 lakh collateral-free, and direct processing across 64 district offices, it removes both the high borrowing costs and bank-intermediary friction that hold smaller enterprises back.
Before visiting your nearest BSCIC District Office, check your credit standing, prepare your trade license and project cost breakdown, and confirm whether your district office currently has revolving fund allocation available for your requested tier. Clean documentation and a realistic repayment plan give your application the strongest chance of approval.
Disclaimer: This article is for general informational purposes only and does not constitute financial or legal advice. Loan limits, interest rates, collateral ceilings, and eligibility rules under BSCIC programs may change by government circular. Always verify current terms directly with your local BSCIC District Office or at bscic.gov.bd before submitting an application.