
Quick answer: Bangladesh Bank’s current master guidance for startup financing is SMESPD Circular No. 02, issued on 9 July 2025. It allows eligible, Bangladesh-registered startups to seek term finance, working-capital finance or equity support through banks and finance companies, subject to the lender’s assessment and available funds. The circular’s maximum customer-level interest/profit rate for term and working-capital finance is 8% a year; that is a ceiling, not a guaranteed offer. The published stage ceilings are BDT 2 crore for a business registered less than two years, BDT 5 crore for two to six years, and BDT 8 crore for six to twelve years. Apply to a bank or finance company, not directly to Bangladesh Bank.
Updated 16 November 2026. Bangladesh Bank and lender terms can change. Confirm the latest circular, participating lender, available allocation and written offer before making a financing decision.
What is the Bangladesh Bank startup financing scheme?
Bangladesh Bank’s startup financing framework is a policy route through regulated banks and finance companies. It is designed for innovative, scalable ventures and lets lenders provide customer finance from their own loanable or investable funds, then seek refinance from Bangladesh Bank’s BDT 500 crore revolving Startup Fund when eligible. The central bank does not make the borrower’s loan decision or send money directly to an entrepreneur. The lender evaluates the application and remains responsible for credit approval and collection.
The 9 July 2025 master circular also provides for equity financing. That is different from a loan: an equity investor receives shares and the business does not make scheduled loan instalments under the equity investment itself. Applicants should ask which route a particular institution actually offers and review the written terms carefully.
One especially important detail is the difference between the rate paid by a lender to Bangladesh Bank for refinance and the rate charged to a customer. The circular specifies 0.50% for refinance to a participating lender, while setting a maximum 8% customer-level rate for term and working-capital finance. Do not interpret the 0.50% inter-institution rate as the rate available to your startup.
Bangladesh Bank startup loan limits by business age
The circular groups loan or investment ceilings by the startup’s registration age. Term finance and working-capital finance are combined when applying the maximum ceiling, so the listed amount is not a separate maximum for each product.
| Stage in the circular | Time since business registration | Maximum combined loan/investment ceiling |
|---|---|---|
| Early stage | Less than 2 years | BDT 2 crore |
| Mid stage | 2 to 6 years | BDT 5 crore |
| Large stage | 6 to 12 years | BDT 8 crore |
These are policy ceilings, not an entitlement or a promise of approval. A bank can approve a smaller amount or decline an application after reviewing the business, repayment capacity, project risks and its own credit policy. A business older than twelve years does not meet the age window stated for this startup framework, though other SME or commercial products may be relevant.
Bangladesh Bank’s circular also sets equity investment ceilings by stage: up to BDT 2 crore for seed-stage ventures, BDT 5 crore for growth-stage ventures and BDT 8 crore for high-growth and scalable ventures. Equity selection follows a separate investment process and can involve ownership dilution. Do not assume a loan applicant can automatically access the equity allocation.
Who may qualify for startup financing in Bangladesh?
The circular does not treat every newly opened shop or company as a startup. It defines a startup around a technology-based business or industrial venture, or a joint venture, with potential to scale and an innovative product or service. It also covers innovation or development in products, services, processes or technology. A venture formed merely by restructuring or splitting an existing business is not counted as a startup under the definition.
Before applying, check these core conditions in the circular and with the lender:
- Bangladesh registration: The startup entity must be registered in Bangladesh.
- Startup fit: The business should satisfy the circular’s innovation, technology or intellectual-property, and scalability criteria. Prepare evidence of the product, process, customer problem and route to growth.
- Business age: The existing venture must be within the twelve-year registration window, with the stage ceiling depending on age.
- No loan default: The circular says financing is unavailable if the venture or any one of its entrepreneurs is a loan defaulter. Ask the lender how it checks credit status and resolve inaccurate records before applying.
- Entrepreneur age for IT ventures: The circular states a minimum age of 21 for IT ventures/entrepreneurs. Confirm how the selected lender applies this provision to your specific business.
- Not a large-company spin-off: A large industry or company cannot label a newly created initiative as a startup to obtain this facility.
Startups nominated or rewarded through a startup-hunting programme run by a government or private institution, university, or national or international organization receive priority under the circular. “Priority” does not mean automatic eligibility or approval; the lender still assesses the application.
Interest rate, repayment period and collateral
What rate does the circular set?
The circular sets a maximum customer-level interest/profit rate of 8% for term and working-capital finance under the framework. It says the rate is applied quarterly on a compound basis. The actual sanctioned rate and calculation should be confirmed in the institution’s written offer. A particular lender may quote a lower rate under its product or an available refinance allocation; for example, ONE Bank’s Notun Uddyog page advertises 4% per year under the Bangladesh Bank refinance facility subject to fund availability and other conditions. This is a bank-specific offer, not a universal rate.
Check whether the quoted annual rate is fixed or variable, how it is calculated, when it is charged, and whether other charges apply. Ask for an instalment schedule and total repayment illustration. Fees, legal costs, valuation, insurance, account requirements and late-payment charges can materially affect the effective cost.
How long can repayment take?
For term finance, the circular permits a maximum customer-level term of eight years including any grace period. Depending on the venture, the grace period may range from three months to two years. Working-capital finance may be renewable based on the banker-customer relationship, up to eight years from the first disbursement; renewal after eight years may be at market-based rates. A grace period does not erase interest/profit or fees unless the sanction letter explicitly says so.
Is the loan collateral-free?
The master circular does not state a general collateral waiver. It requires approval under the bank’s or finance company’s own lending policy. Security, guarantees and other conditions can depend on the institution, amount, purpose and risk review. Do not rely on a social-media post or an old advertisement claiming that every startup loan is unsecured. Ask the lender to list required collateral, guarantors, valuation costs and any exceptions in writing.
How to apply for a startup loan in Bangladesh
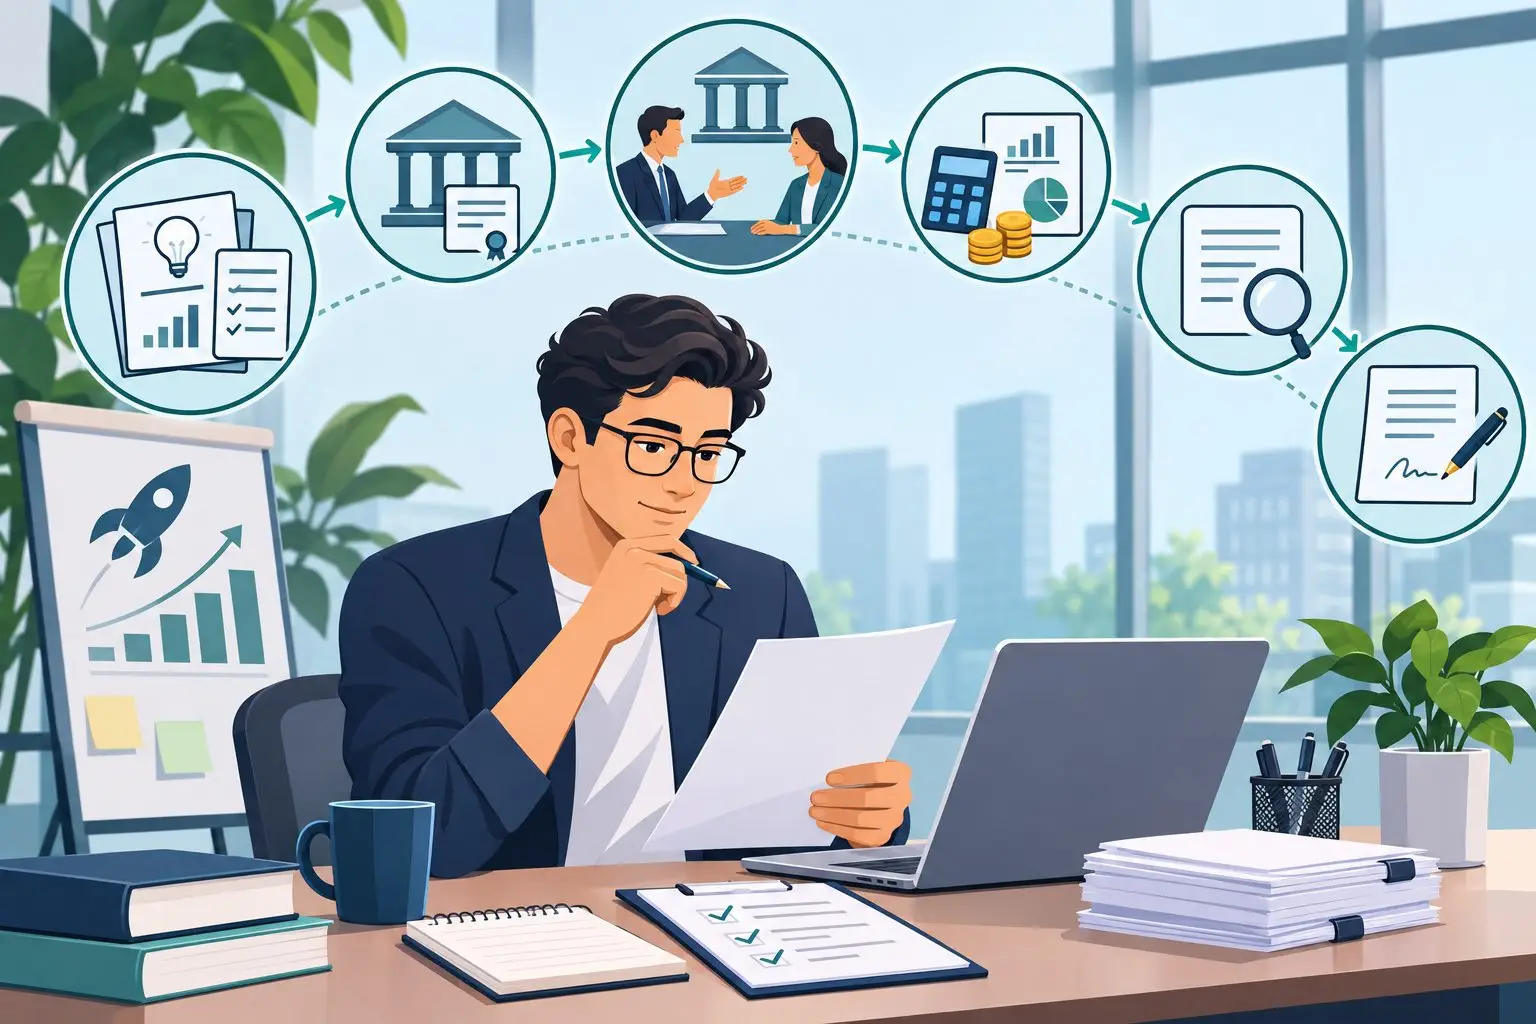
- Check that the venture fits the policy definition. Describe the innovation, technology or intellectual-property element, customer need, evidence of demand and how the business can scale. Explain why the proposal is not simply a restructuring of an existing business.
- Confirm registration age and borrower status. Gather the entity’s registration or incorporation evidence and calculate age from the registration date. Ask the lender what credit checks it will perform for the company and each entrepreneur.
- Choose a regulated bank or finance company. Ask the SME/startup desk whether it currently accepts applications under the Bangladesh Bank startup framework, whether a relevant refinance allocation is available and whether it offers debt, equity or both. The list of institutions and available funding can change.
- Define the amount and use. Split the request into term finance and working capital. Link each amount to a business use such as equipment, product development, inventory or launch costs, and show why the combined request remains within the relevant stage ceiling.
- Prepare a repayment-ready proposal. Include the product or service, target customers, pricing, sales evidence, operating costs, cash-flow forecast, risks, management experience, owner contribution and repayment source. Use conservative assumptions and explain what happens if sales grow more slowly than planned.
- Submit the lender’s form and evidence. Provide the requested company, owner, financial and security documents. Keep copies and ask for a receipt or application reference. Respond promptly to due-diligence requests.
- Compare the sanction terms before signing. Review the approved amount, purpose, rate, quarterly calculation, repayment schedule, grace period, fees, collateral, covenants, disbursement conditions, late charges and early-settlement rules. Ask for unclear terms to be explained in writing.
Bangladesh Bank’s circular describes a lender-led process: the institution evaluates the proposal and makes the customer-level financing decision under its own policy. A central-bank refinance arrangement supports eligible lenders after they disburse qualifying financing; it does not replace the lender’s borrower assessment. Avoid anyone who claims they can guarantee approval or asks for an unofficial fee to “release” Bangladesh Bank funds.
Documents to prepare before speaking to a lender
The central-bank circular sets the programme rules, but individual institutions set their application forms and document checklists. The following is a preparation list, not a universal or official checklist. Ask the selected lender for its current requirements before submitting originals.
- Company incorporation/registration documents, trade licence and current business address
- Owners’ or directors’ NID details, contact information and ownership structure
- e-TIN and available tax-return or tax-compliance records
- Business bank statements, sales records and management accounts
- Business plan, product details, market evidence and financial projections
- Cash-flow forecast showing how the business will repay the facility
- Supplier quotations, purchase orders, invoices or equipment specifications for the proposed use
- Relevant intellectual-property, software, technology, prototype or regulatory documents where they support the startup case
- Property papers, valuation information or guarantor documents only if the lender requests security
- Board resolutions, partnership deed or other authorization documents where applicable
Organize the documents so the requested amount can be traced to specific costs. Separate actual sales from forecasts. Label assumptions, and do not inflate customer numbers or expected revenue. A clear application helps the credit team assess the proposal; it does not guarantee an outcome.
Startup loan, SME loan or equity: which route fits?
| Funding route | Potential fit | Main consideration |
|---|---|---|
| Startup term/working-capital finance | An eligible innovative venture with a defined use and a plausible repayment source | Repayment and lender conditions apply; the ceiling is not an automatic approval. |
| Other SME or new-entrepreneur finance | A small business that does not meet the startup definition or needs a different product | Eligibility, rates, security and refinance terms vary by scheme and lender. |
| Equity investment | A scalable business seeking risk capital and able to share ownership | Founders may give up shares or governance rights; review valuation and exit terms. |
Debt can preserve ownership but creates repayment obligations even when business revenue disappoints. Equity can reduce scheduled debt service but dilutes ownership and may give investors governance or information rights. Compare the cost, control and risk over the full life of the funding, not only the amount received on day one.
For a wider view of borrowing options, see BusinessPathsala’s guides to comparing banks for SME loans, entrepreneur loans in Bangladesh, and starting a small business in Bangladesh.
How to verify a scheme or offer is current
Rules and money available through a refinance line are not the same thing. Before relying on a rate or limit, check the latest Bangladesh Bank circular and ask the institution whether it is currently participating, accepting applications and able to process a startup case under the facility. Ask for the product sheet and a dated written quotation. Confirm which terms come from the central-bank framework and which are the lender’s own conditions.
Do not treat a published ceiling as a current funding guarantee. The 2025 circular creates a framework and describes the refinance fund; a bank may have its own intake process, risk appetite, internal documentation, and allocation status. If an institution says a scheme is temporarily unavailable, ask whether it expects an update or can consider another product without implying that the alternative is equivalent.
Common mistakes to avoid
- Assuming every new business is a startup. The policy focuses on innovative, scalable ventures and excludes a simple restructuring or division of an existing business.
- Confusing the lender refinance rate with the borrower rate. The circular’s 0.50% refinance rate is for participating institutions; the customer ceiling is different.
- Believing a maximum limit is promised. BDT 2, 5 or 8 crore is a stage ceiling. The lender decides whether to approve a smaller amount or decline the case.
- Using a short-term facility for a long-lived asset. Match the financing period to how quickly the business asset generates cash.
- Ignoring quarterly compounding or fees. Ask for the complete payment schedule and total cost, including lender-specific charges.
- Applying before checking default records. The circular’s non-defaulter condition includes entrepreneurs; clarify and correct data issues with the lender before submission.
- Paying intermediaries who promise guaranteed approval. Apply through the lender’s official channel and verify all fees with the branch or official website.
Frequently asked questions
Does Bangladesh Bank give startup loans directly to founders?
No. Apply to a participating bank or finance company. The lender assesses the borrower, approves or declines the request, and may seek refinance from Bangladesh Bank after disbursement if the loan qualifies.
What is the maximum Bangladesh Bank startup loan?
The July 2025 circular gives combined term and working-capital finance ceilings of BDT 2 crore for a startup registered under two years, BDT 5 crore at two to six years, and BDT 8 crore at six to twelve years. The lender’s approval and available funds determine the amount actually offered.
Is the startup loan interest rate 4%?
Not as a universal rule. The circular sets a maximum customer-level rate of 8% for term and working-capital finance under the framework. Some lender products advertise a lower rate, such as 4%, subject to the product’s conditions and refinance-fund availability. Get the current written offer from the lender.
Can a startup apply without collateral?
The master circular does not create a blanket collateral-free entitlement. Security and guarantees depend on the selected institution’s credit policy and sanction terms. Ask the lender what it requires for your amount and business profile.
Can a pre-revenue startup apply?
The circular’s startup definition does not promise approval to pre-revenue applicants. A founder should be ready to demonstrate product progress, customer need, scalability, use of funds and a credible repayment or investment case. The bank or finance company decides whether the evidence is sufficient.
What is the difference between a startup loan and equity finance?
A loan or investment facility under the lender’s credit process generally creates repayment obligations under the contract. Equity gives an investor ownership shares and may involve governance rights, but it does not work like a scheduled loan. Read the specific documents and consider independent legal and financial advice before signing.
Can a business more than 12 years old use the startup facility?
The circular limits existing startup ventures under this framework to businesses registered no more than twelve years ago. Older businesses may explore other SME or commercial financing, subject to separate eligibility and lender terms.
Official sources and further reading
- Bangladesh Bank, SMESPD Circular No. 02, Master Circular on Start-up Financing (9 July 2025) — definition, eligibility, stage ceilings, rates, tenure and lender process.
- Bangladesh Bank SME & Special Programmes Department circular portal — check for later notices and circulars.
- ONE Bank Notun Uddyog product page — an example of lender-specific startup terms, subject to fund availability and conditions.
- Bangladesh Bank Annual Report 2024–2025 — broader context on refinance schemes and SME financing.
Bottom line
Startup loan financing in Bangladesh is possible under Bangladesh Bank’s July 2025 framework, but the borrower applies through a bank or finance company and remains subject to its credit assessment, current funding availability and sanction terms. Check whether the venture meets the policy definition, use the relevant registration-age ceiling as a maximum only, and compare the written rate, fees, security and repayment schedule before signing.
Financial information notice: This guide is for general education, not a loan offer, investment recommendation or guarantee of financing. Policies and institution-specific terms may change. Verify current requirements directly with Bangladesh Bank and the chosen lender.
