The best bank for an SME loan in Bangladesh depends on your business profile rather than a single universal winner: BRAC Bank PLC leads in nationwide collateral-free MSME reach and women-entrepreneur support, City Bank PLC and Eastern Bank PLC (EBL) offer the highest unsecured limits (up to BDT 1.50–2.00 crore) for established firms, Prime Bank PLC excels in 4%–5% Bangladesh Bank-refinanced startup and women’s loans, and Sonali Bank PLC or Pubali Bank PLC suit district-level borrowers seeking lower-cost, wide-branch access.
Choosing the wrong bank wastes months of paperwork and can lock your business into heavy property mortgages or mismatched repayment schedules. Since Bangladesh Bank withdrew the SMART-based lending rate cap in May 2024, commercial banks now price SME facilities based on risk, collateral, and deposit costs. That makes comparing product structures—not just advertised rates—essential before you submit a loan file.
This guide compares eight leading conventional, state-owned, and Shariah-compliant banks in Bangladesh using verified 2025–2026 product terms, central bank refinance rules, and practical eligibility criteria.
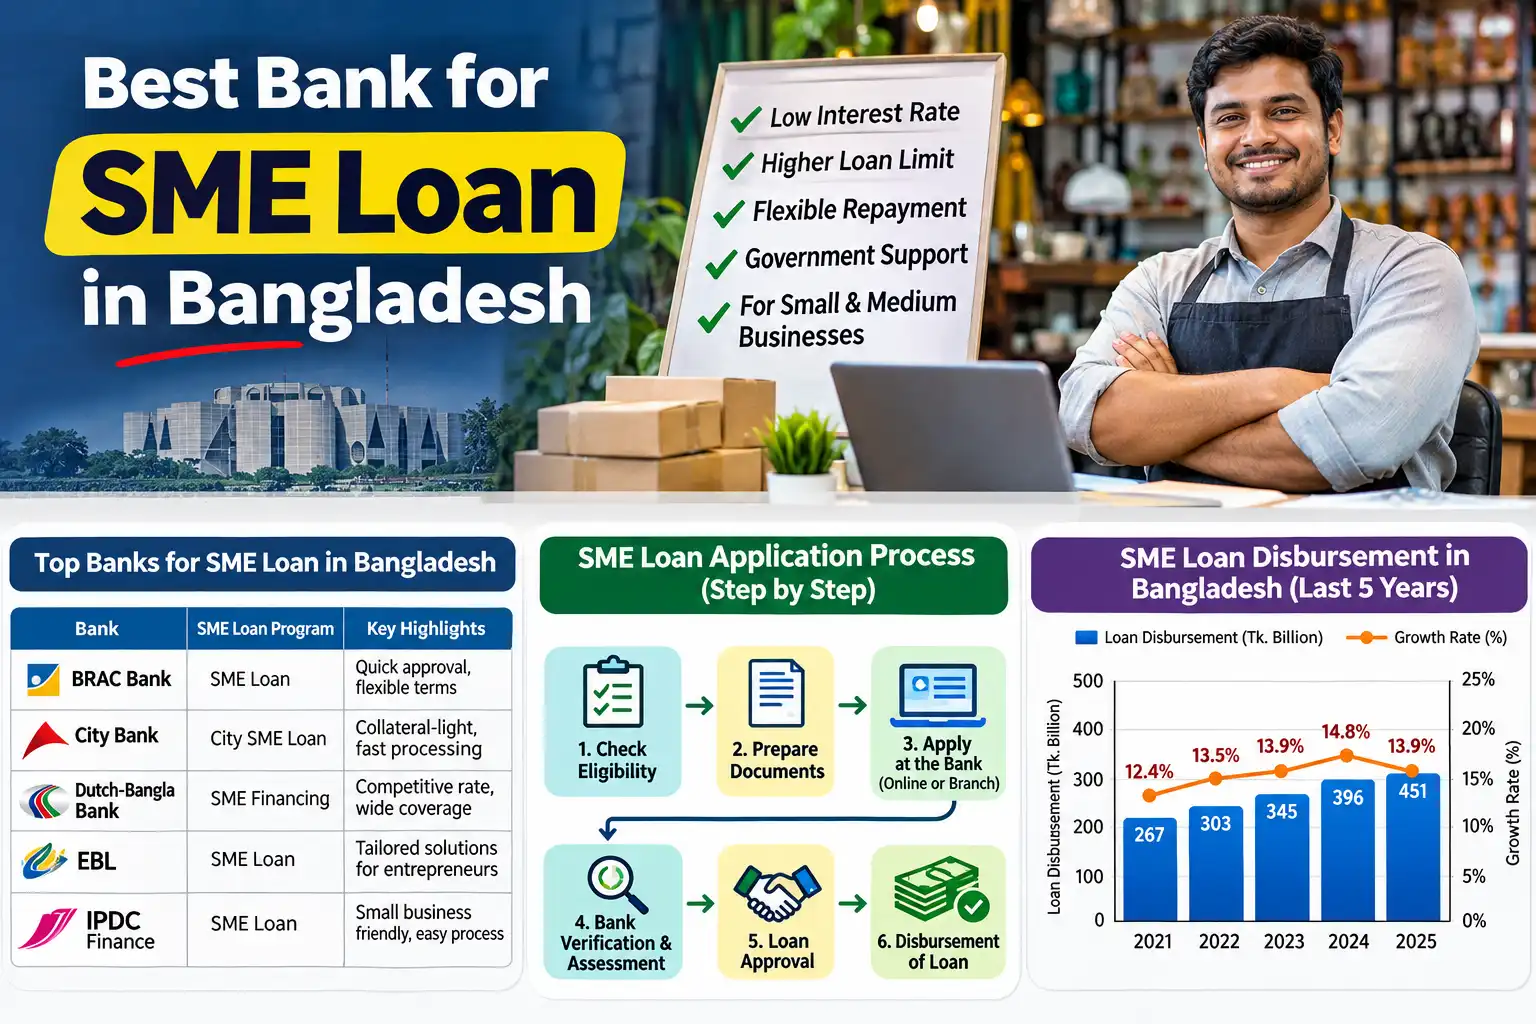
Quick Comparison: Top 8 Banks for SME Loans in Bangladesh (2026)
Before diving into each bank’s eligibility rules, use the table below to shortlist two or three banks that match your required loan amount, collateral availability, and sector.
| Bank | Flagship SME Product(s) | Loan / Investment Limit | Collateral-Free Limit | Tenor | Best For |
|---|---|---|---|---|---|
| BRAC Bank PLC | Anonno, TARA Uddokta, Shomriddhi | BDT 5 lakh – 25 crore | Up to BDT 50 lakh (Anonno); up to BDT 2 crore (TARA) | Up to 48 months (Anonno) | Small traders, cottage/micro firms, & women entrepreneurs |
| City Bank PLC | City SME Small Loan, City Alo | Up to BDT 5 crore | Up to BDT 1.5–2 crore (unsecured options) | Flexible (Term / OD) | Growing SMEs & new-to-credit firms with strong cash flow |
| Eastern Bank PLC (EBL) | EBL Mukti, Utkorsho, Startup, Asha | BDT 1 lakh – 25 crore | Up to BDT 1.5 crore (Utkorsho); BDT 1 crore (Mukti/Startup) | 3 – 60 months (up to 84m fleet) | Established unsecured borrowers, startups, & women-led firms |
| Prime Bank PLC | Prime Anchol, Prime Startup, Chalti | Up to BDT 1.5 crore (Anchol) | Up to BDT 50 lakh (Prime Anchol) | Up to 5 years | Refinanced 4%–5% startup & women’s loans, trade finance |
| Sonali Bank PLC | Sonali Bank SME Loan | BDT 50,000 – 100 crore | BDT 5 lakh (men); BDT 25 lakh (women) | Up to 7 years (project); 1 yr (WC) | Upazila/rural enterprises & long-tenor project finance |
| Pubali Bank PLC | PBL Subarna, Karma Uddog, Sujan | BDT 2 lakh – 10 lakh (Special SME) | Up to BDT 10 lakh | 12 – 36 months | Semi-urban traders, machinery buyers, & quick micro-SMEs |
| Mutual Trust Bank PLC (MTB) | Small Business Loan Plus, Shurokkha, Uddog | Up to BDT 1 crore (SBL Plus); 25–35L (Shurokkha) | Varies by scheme (Agri DL up to 10L) | Short-term to multi-year | Competitive trade rates, agro-processing, & cluster borrowers |
| Social Islami Bank PLC (SIBL) | Baim-SME, HPSM-SME, Bai-Muajjal | Up to BDT 50 lakh (Small); BDT 5 lakh (Micro) | Per bank/BB policy (up to BDT 25L guideline) | Revolving / Installment | Shariah-compliant asset & working capital financing |
Note: Bank limits, collateral waivers, and interest or profit rates depend on your Credit Information Bureau (CIB) record, business vintage, and branch-level risk assessment. Always confirm current sanction terms with the bank’s SME desk.
How SME Loan Interest Rates Work in Bangladesh (2026 Reality Check)
In Bangladesh, SME loan pricing falls into two distinct tiers: market-based commercial bank rates and subsidized government or Bangladesh Bank refinance schemes. Mixing these two tiers together is the most common mistake first-time applicants make.
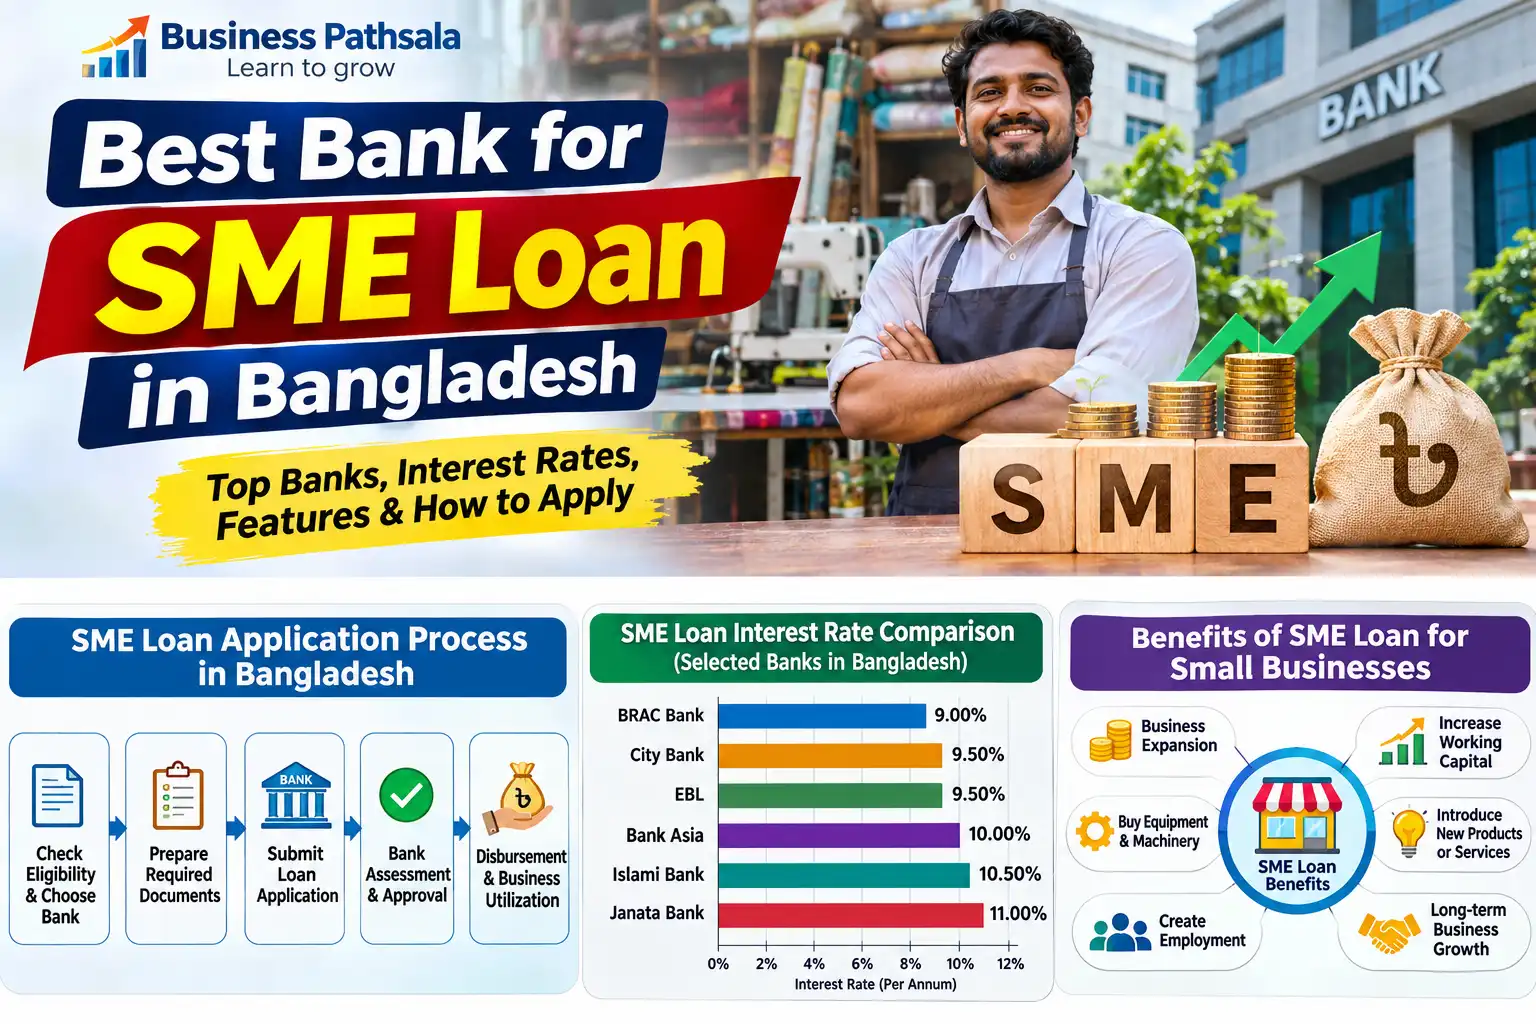
For standard commercial SME term loans and working capital facilities, publicly posted bank rates in 2026 generally range between 12.5% and 16.0% per annum, depending on the bank, sector, and borrower risk profile (as tracked in 2026 public bank rate comparisons). By contrast, targeted policy schemes managed by Bangladesh Bank’s SME & Special Programmes Department (SMESPD) and the SME Foundation cap customer rates much lower:
- Bangladesh Bank Startup Refinance Scheme (SMESPD Circular 02): Capped at 4.0% per annum for eligible innovative startups, with tenors up to 8 years including a grace period.
- Small Enterprise Refinance Scheme for Women Entrepreneurs: Capped at a maximum of 5.0% per annum at the customer level (for cottage, micro, and small enterprises where women hold at least 51% ownership), plus a 2% good-borrower/PFI incentive upon timely repayment.
- Bangladesh Bank Tk 25,000 Crore CMSME Pre-Finance/Refinance Scheme: Capped at a maximum of 7.0% per annum for eligible manufacturing, service, and trading CMSMEs, with at least 75% of funds earmarked for cottage, micro, and small businesses.
- SME Foundation Credit Wholesaling Programme (2026 Allocation): Priced at 8.0% per annum for loans between BDT 1 lakh and BDT 25 lakh disbursed through 15 partner banks and NBFIs, with no collateral required up to BDT 10 lakh, as reported by The Business Standard in April 2026.
If you want a deeper breakdown of how banks calculate reducing-balance EMIs versus overdraft charges, read our dedicated SME loan interest rate guide for Bangladesh.
Detailed Review of the Best Banks for an SME Loan in Bangladesh
1. BRAC Bank PLC — Best Overall for Micro, Small & Women-Led Businesses
BRAC Bank PLC is widely recognized as Bangladesh’s pioneer in formal MSME banking, operating dedicated SME unit offices and branch desks across urban and semi-urban districts. Its model is built around assessing cash flow rather than demanding land deeds from small traders.
- Flagship Products: Anonno (BDT 5 lakh to 50 lakh, completely mortgage-free, up to 48 months tenor), Anonno Plus, Shomriddhi (BDT 5 lakh to 25 crore for larger facilities), and TARA Uddokta SME Loan.
- Women Entrepreneur Advantage: Under TARA Uddokta, eligible women-owned enterprises can access financing at 5% interest up to BDT 1 crore (subject to Bangladesh Bank refinance allocation) and unsecured loans up to BDT 2 crore.
- Seasonal Flexibility: Anonno allows single-installment facilities tailored for businesses with seasonal revenue peaks (such as Eid retail or agro-trading).
- Limitations: Standard non-refinanced commercial rates are not published as a single flat figure on product pages and can sit in the mid-teens once risk-adjusted.
2. City Bank PLC — Best for High Unsecured Limits & New-to-Credit Growth Firms
City Bank PLC has aggressively expanded its small-business portfolio to serve both established trading houses and promising new-to-credit enterprises that lack traditional real-estate collateral.
- Flagship Products: City SME Small Loan and City Alo (women’s banking proposition).
- Loan Limits & Collateral: Access up to BDT 5 crore for secured facilities and BDT 1.5 crore to 2 crore unsecured, depending on turnover and credit assessment.
- Facility Mix: Offers term loans, revolving overdrafts (OD), and single-installment options across trading, manufacturing, services, and agro-based sectors.
- Limitations: While City Bank advertises collateral-free options for high-potential new-to-credit firms, applicants without strong bank-statement turnover may still be asked for personal guarantees or partial cash security.
3. Eastern Bank PLC (EBL) — Best for Specialized Unsecured & Startup Loans
Eastern Bank PLC stands out for segmenting its SME loan lineup by exact business maturity and purpose, making it easier for applicants to see where they qualify before applying.
- EBL Utkorsho: Unsecured loan from BDT 30 lakh to BDT 1.50 crore (24–48 months) for businesses with 4–5 years of operating history and verifiable bank transactions.
- EBL Mukti (Women Entrepreneurs): Unsecured financing from BDT 1 lakh to BDT 1 crore (24–60 months) for businesses aged 2–3 years; no bank transactions required for loans up to BDT 30 lakh.
- EBL Startup: Unsecured facility from BDT 2 lakh to BDT 1 crore (24–60 months) for innovative technology, product, or service startups—with no minimum business age or prior bank transaction requirement.
- EBL Asha & Secured Options: EBL Asha covers smaller unsecured needs (BDT 2 lakh to 20 lakh), while EBL Business Solution and EBL Cash Credit scale up to BDT 10 crore against registered property mortgages.
- Limitations: EBL’s branch footprint is concentrated in major cities and industrial hubs rather than remote rural upazilas.
4. Prime Bank PLC — Best for Refinanced 4%–5% Schemes & Trade-Linked SMEs
Prime Bank PLC combines transparent public rate disclosures with strong participation in Bangladesh Bank’s concessional refinance windows and import-export trade finance.
- Flagship Products: Prime Anchol (up to BDT 1.5 crore, tenor up to 5 years, no collateral required up to BDT 50 lakh, 5% interest upon Bangladesh Bank refinance), Prime Startup (4% under Bangladesh Bank startup policy), Prime Chalti, and Prime Dealer.
- Why Borrowers Pick Prime Bank: As of April 2026 public rate sheets, Prime Bank’s posted commercial rates sit around 14.00% for standard SME term/working capital and 13.00% for trade lending—giving borrowers a clear benchmark before negotiating.
- Limitations: Prime Anchol requires at least 1 year of business experience, one family personal guarantee, and one third-party personal guarantee (or property mortgage if a third-party guarantor is unavailable).
5. Sonali Bank PLC — Best State-Owned Bank for Rural Reach & Long Tenors
If your workshop, agro-processing unit, or retail business operates outside major metropolitan hubs, Sonali Bank PLC provides unmatched nationwide branch coverage and long project repayment windows.
- Loan Limits & Tenor: From BDT 50,000 up to BDT 100 crore (depending on project feasibility), with project loans running up to 7 years and working capital lines renewable annually.
- Collateral Policy: Collateral-free up to BDT 5 lakh for male entrepreneurs and up to BDT 25 lakh for women entrepreneurs.
- Equity Requirement: Standard debt-to-equity ratios are 60:40 for project loans and 70:30 for working capital—meaning you must invest 30%–40% of the capital yourself.
- Limitations: Branch-level file processing and verification can take noticeably longer than fast-track private banks, and larger facilities require tangible collateral.
6. Pubali Bank PLC — Best for Fast Micro-SME & Machinery Loans Up to BDT 10 Lakh
Pubali Bank PLC has one of the largest private-sector branch networks in Bangladesh and offers three straightforward, collateral-free Special SME Products tailored for smaller enterprises.
- PBL Subarna (Working Capital): BDT 2 lakh to 10 lakh, 12/24/36 months, EMI repayment with 1–3 months grace period.
- PBL Karma Uddog (Women Entrepreneurs): BDT 2 lakh to 10 lakh, 12/26/36 months, collateral not mandatory.
- PBL Sujan (Machinery & Vehicles): BDT 2 lakh to 10 lakh for capital machinery, office equipment, or delivery vans, collateral not mandatory up to BDT 10 lakh.
- Limitations: Special collateral-free products cap out at BDT 10 lakh; larger expansion loans require standard corporate or commercial security.
7. Mutual Trust Bank PLC (MTB) — Best for Trade Finance & Agro-Cluster SMEs
Mutual Trust Bank PLC offers a deep suite of CMSME and agro-industrial products alongside active participation in SME Foundation credit wholesaling agreements.
- Flagship Products: Small Business Loan Plus (up to BDT 1 crore), MTB Shurokkha (BDT 25–35 lakh funded + non-funded), MTB Uddog (revolving short-term), MTB Krishijat (agro-processing), and MTB Agri DL (collateral-free up to BDT 10 lakh).
- Rate & Scheme Advantage: MTB’s May 2026 published wholesale/retail trade rate of 12.50% (and 14.50% for standard SME term/working capital) is competitive, and its 2026 SME Foundation Credit Wholesaling agreement channels 8% loans to priority clusters and women-led enterprises.
- Limitations: Higher-limit facilities often combine funded loans with non-funded instruments (like LCs or bank guarantees), which suit traders more than pure local service shops.
8. Social Islami Bank PLC (SIBL) — Best for Shariah-Compliant SME Investment
For entrepreneurs who prefer interest-free Islamic banking modes—such as Bai-Muajjal (deferred-payment sale), Murabaha (cost-plus trade), or HPSM (Hire Purchase under Shirkatul Melk)—Social Islami Bank PLC (SIBL) and full-fledged Islamic windows of conventional banks (such as Prime Bank Islamic or Pubali Islamic) provide structured alternatives.
- Flagship Products: Baim-SME (Revolving), HPSM-SME (Commercial & Transport), and Bai-Muajjal Commercial Installment—each offering up to BDT 50 lakh for small enterprises, plus Baim-ME up to BDT 5 lakh for micro-enterprises.
- How It Works: Instead of lending cash at interest, the bank purchases the machinery, vehicle, or inventory and sells or leases it to your business at an agreed markup or profit-sharing schedule.
- Limitations: Because Shariah contracts require underlying asset or trade documentation (invoices, quotations, delivery challans), pure cash-working-capital requests take extra documentation.
How to Choose the Right Bank for Your Specific Business Profile
Instead of applying blindly to the nearest branch, match your business stage and asset base to the right banking tier using the four-pillar framework below.
1. If You Have No Property Collateral (Unsecured / CGS-Backed)
Under Bangladesh Bank’s SME Credit Policy guidelines, banks may extend collateral-free credit up to BDT 25 lakh against personal guarantees, and leading private banks go even higher using their own risk scoring or Bangladesh Bank’s Credit Guarantee Scheme (CGS). Shortlist BRAC Bank (Anonno) for BDT 5–50 lakh, Pubali Bank (Subarna/Sujan) for BDT 2–10 lakh, or City Bank / EBL (Utkorsho) if your annual turnover supports BDT 30 lakh–1.50 crore unsecured.
2. If You Are a Woman Entrepreneur (51%+ Ownership)
Always ask for a 5% Bangladesh Bank Women Entrepreneur Refinance slot before accepting a standard 14% commercial rate. BRAC Bank (TARA Uddokta), EBL (Mukti), Prime Bank (Prime Anchol), and City Bank (City Alo) have dedicated women’s desks and higher collateral-free ceilings. Note that refinance funds are subject to Bangladesh Bank quota availability at the time of disbursement.
3. If You Are a New Business or Tech-Enabled Startup
Traditional SME loans usually require 1 to 3 years of profitable operations. If you are a registered startup developing an innovative product or digital service, target EBL Startup (no minimum business age) or Prime Startup under Bangladesh Bank’s 4% Startup Refinance Scheme. If you operate a conventional new shop or service without innovation criteria, explore Sonali Bank or SME Foundation-partnered banks, or review our guide on Uddokta loan eligibility and options in Bangladesh.
4. If You Need Working Capital vs. Machinery Purchase
Never use a short-term Overdraft (OD) or Cash Credit (CC) line to buy factory machinery—you will face annual renewal pressure on long-term assets. Match Term Loans (2–7 years) to machinery, renovation, or commercial vehicles, and use CC (Hypothecation) / OD facilities strictly for inventory cycles and receivables.
SME Loan Eligibility Criteria & Document Checklist in Bangladesh
Most Bangladeshi banks reject or delay SME applications not because the business is unprofitable, but because the paperwork is incomplete or inconsistent. Below are the standard baseline requirements aligned with Bangladesh Bank’s SMESPD guidelines.
Standard Eligibility Criteria
- Citizenship & Age: Bangladeshi citizen, typically aged 21 to 65 years (18+ at some state-owned banks like Sonali Bank).
- Business Vintage: Usually 1 to 3 years of continuous operation in the same line of business (waived only for specific startup or new-entrepreneur schemes).
- Clean CIB Report: No overdue, classified, or defaulted loans in Bangladesh Bank’s Credit Information Bureau (CIB) for either the business owner or the proposed guarantor.
- Legal Registration: Active business entity (sole proprietorship, registered partnership, or private limited company).
Complete Document Checklist
- Identity Documents: National ID (NID) and recent passport-size photographs of the applicant(s) and guarantor(s).
- Updated Trade License: Valid, renewed Trade License from your City Corporation, Pourashava, or Union Parishad. (If you are still setting up your business paperwork, see our guide on how to start a business in Bangladesh.)
- Tax Registration: Valid 12-digit e-TIN Certificate and recent tax return acknowledgment (PSR). Need one? Follow our step-by-step tutorial on getting an e-TIN certificate online in 5 minutes.
- Premises Proof: Commercial rent/lease agreement, or ownership deed plus recent utility (electricity/gas) bill.
- Entity Formation Papers: Notarized partnership deed (for partnerships) or Certificate of Incorporation, Memorandum & Articles of Association (for Private Limited companies).
- Bank Statements: Last 12 months of business (and personal, if proprietorship) bank statements showing regular sales deposits.
- Financial & Stock Records: Sales and expense ledgers or audited/management accounts for the past 1–3 years, plus a current inventory/stock valuation list.
- Guarantor Package: Guarantor’s NID, photo, net-worth statement, and Trade License (if a businessperson) for CIB verification.
- Sector Licenses (If Applicable): BIN/VAT registration, Import/Export Registration Certificates (IRC/ERC), BSTI, or environmental clearance.
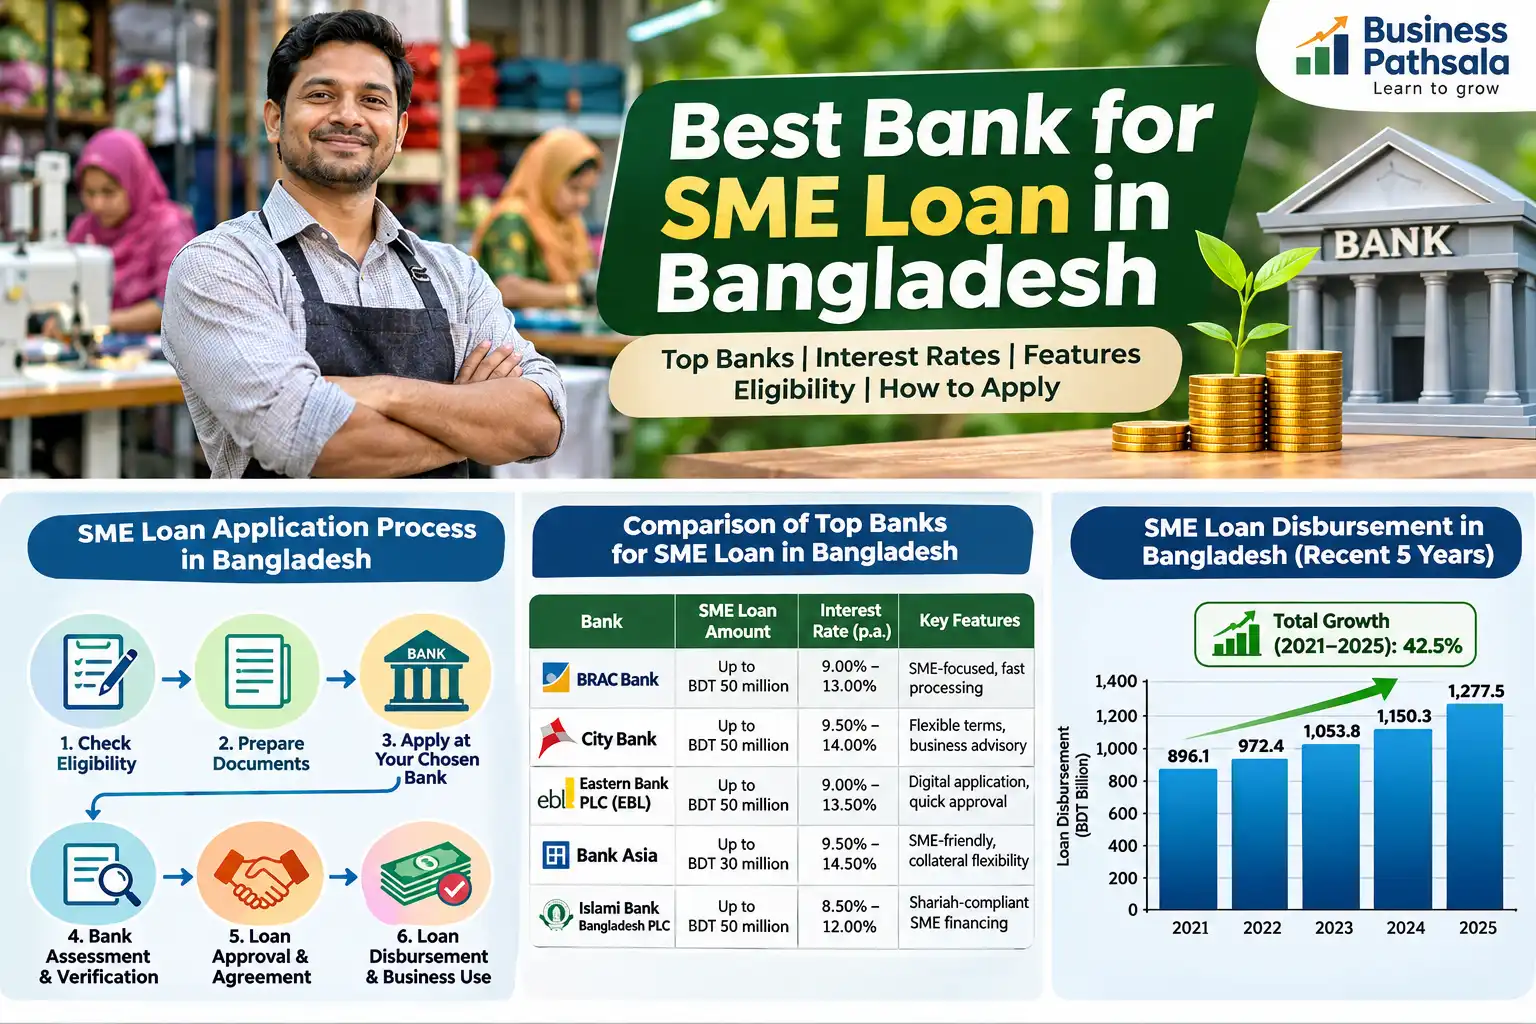
Step-by-Step: How to Apply for an SME Loan in Bangladesh
- Run a Self-Check on Your CIB & Cash Flow: Clear any overdue credit card bills or mobile-banking micro-loans before applying. Even a BDT 2,000 overdue balance flags your CIB report.
- Calculate Your Realistic EMI Capacity: Keep total monthly loan repayments below 35%–45% of your average net monthly business cash surplus. For example, on a BDT 15 lakh loan at 14.0% over 36 months, your monthly EMI is roughly BDT 51,266—ensure your slow-season months can comfortably cover that amount.
- Shortlist 2–3 Banks (1 Subsidized + 1–2 Commercial): Check whether you qualify for a 5% women’s scheme, 4% startup fund, or 8% SME Foundation window first, and keep a fast-processing private bank as your backup.
- Visit the Dedicated SME Desk (Not Just a General Teller): Ask to speak with the branch’s SME Relationship Officer or visit a dedicated SME Unit Office.
- Submit the Complete File & Request a Written Fee Breakdown: Ask for the processing fee, stamp/documentation charges, early-settlement fee rules (note that Bangladesh Bank rules waive early-settlement fees for cottage and micro industries), and whether the interest rate is fixed or floating.
- Prepare for Physical Site Verification: Bank officers will visit your shop, warehouse, or factory to verify stock, machinery, and daily footfall before sending the file to Credit Risk Management (CRM).
- Review the Sanction Letter Carefully: Before signing, verify the sanctioned amount, interest rate, repricing frequency, grace period, and collateral/personal guarantee clauses.
Common Mistakes, Risks & Warnings for Bangladeshi SME Borrowers
- Chasing Unregulated Online Loan Apps: Legitimate SME bank loans require branch verification and CIB checks. Avoid unverified mobile apps promising “instant business cash without documents,” which often charge predatory fees—read our warning on Bangladesh’s online loan apps and hidden costs.
- Depositing Cash Sales Outside the Bank: Many small traders keep cash in hand or personal bKash accounts instead of routing sales through a business current account. Banks size your loan limit based on visible bank turnover.
- Over-Borrowing on Short Tenors: Taking a 12-month loan for a 3-year factory expansion creates severe cash-flow stress. Always match loan tenor to asset payback time.
- Ignoring Floating-Rate Repricing Clauses: Since the 2024 market-based rate shift, many banks include quarterly or semi-annual repricing clauses in sanction letters. Budget for a 1%–2% rate buffer.
Editorial & Financial Disclaimer: This article is for informational and educational purposes only and does not constitute formal financial, legal, or credit advice. Loan approval is never guaranteed and depends on each bank’s Credit Risk Management (CRM) assessment, CIB clearance, and Bangladesh Bank regulations in force at the time of application.
Frequently Asked Questions (FAQs)
Which bank gives SME loans without collateral in Bangladesh?
Several banks offer collateral-free SME loans in Bangladesh: BRAC Bank PLC (Anonno) offers up to BDT 50 lakh (and up to BDT 2 crore under TARA Uddokta for women), City Bank PLC and Eastern Bank PLC (EBL Utkorsho) offer unsecured loans up to BDT 1.50–2.00 crore for established firms, Prime Bank (Prime Anchol) waives collateral up to BDT 50 lakh, and Pubali Bank offers collateral-free Special SME loans up to BDT 10 lakh.
What is the current SME loan interest rate in Bangladesh in 2026?
Standard commercial SME loans from private banks typically carry interest rates between 12.5% and 16.0% per annum. However, eligible borrowers under Bangladesh Bank or SME Foundation refinance programs can access rates of 4.0% (startups), 5.0% (women entrepreneurs), 7.0% (CMSME Tk 25,000 crore scheme), or 8.0% (SME Foundation credit wholesaling).
Which bank is best for a women entrepreneur SME loan in Bangladesh?
BRAC Bank PLC (TARA Uddokta), Eastern Bank PLC (EBL Mukti), Prime Bank PLC (Prime Anchol), and City Bank PLC (City Alo) are top choices for women entrepreneurs. All four participate in Bangladesh Bank’s 5% women-entrepreneur refinance framework and provide dedicated branch support and high collateral-free limits.
Can a brand-new business get an SME loan in Bangladesh?
Yes, though options are narrower than for 2-year-old businesses. Innovative or tech-enabled startups can apply for EBL Startup (no minimum business age) or Prime Startup under Bangladesh Bank’s 4% Startup Refinance Scheme. Traditional new entrepreneurs with technical training can also explore Bangladesh Bank’s New Entrepreneurs Refinance Scheme (up to BDT 10 lakh collateral-free) through participating banks.
How long does SME loan approval take in Bangladesh?
With a complete document file and clean CIB report, private commercial banks typically take 2 to 4 weeks from application submission to disbursement for standard unsecured or small SME loans. Mortgaged facilities and state-owned bank project loans can take 4 to 8 weeks due to property legal vetting and valuation.
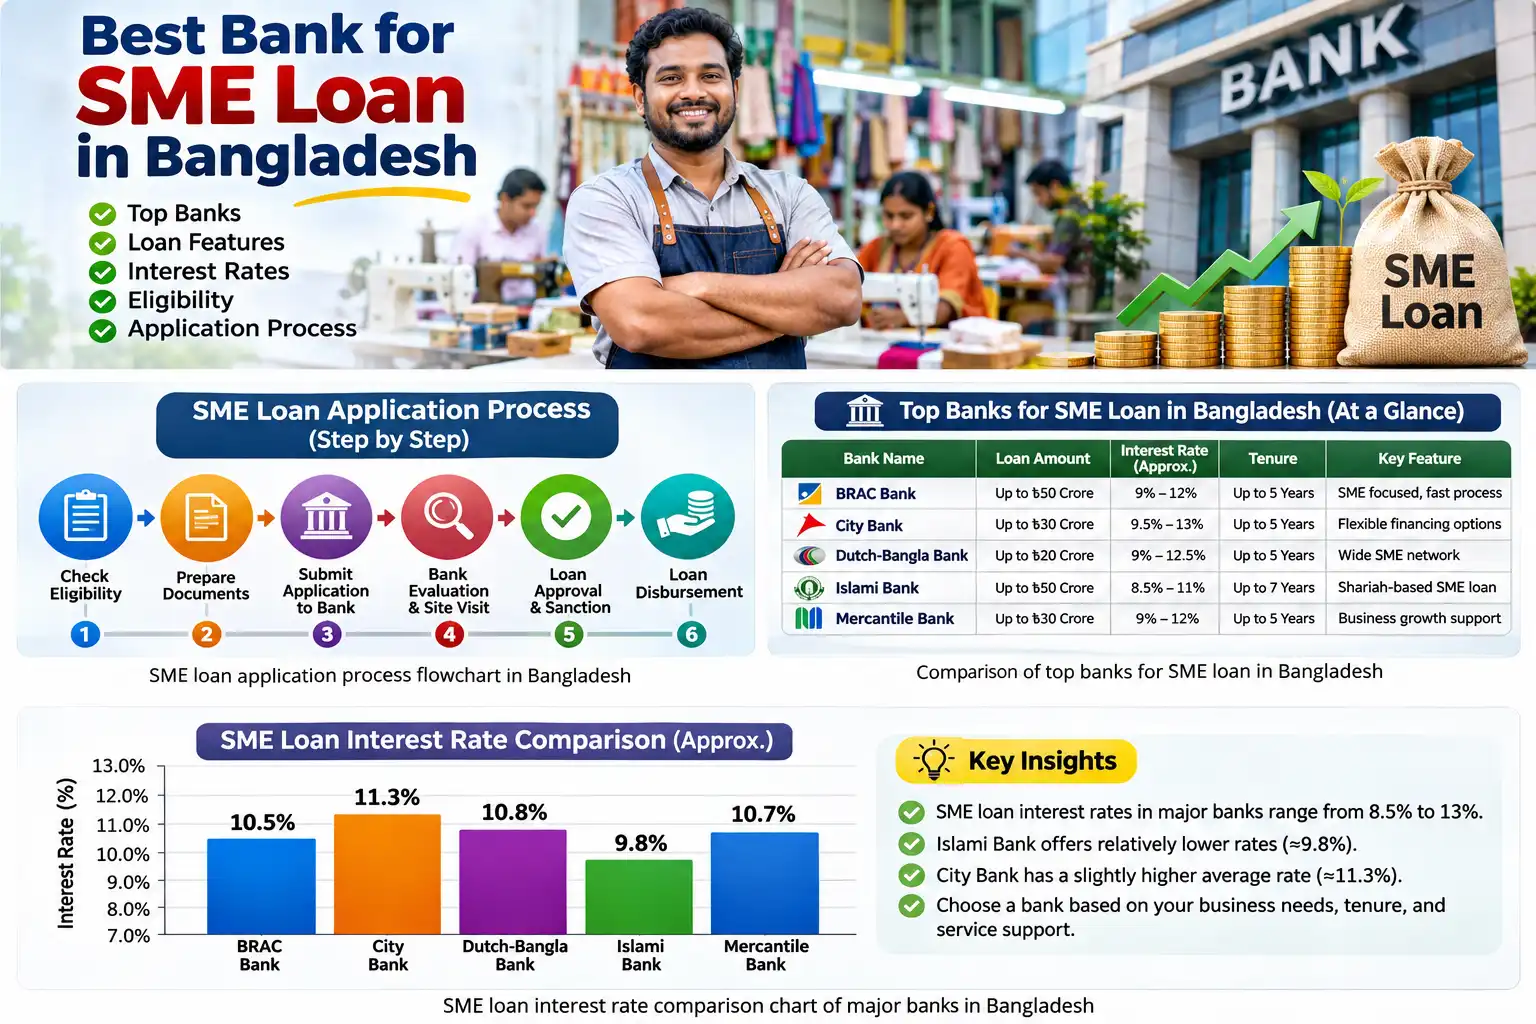
Conclusion: Your Next Step
There is no single “best” SME bank for every entrepreneur in Bangladesh—the right choice matches your collateral capacity, sector, and urgency. If you need fast, collateral-free working capital, start with BRAC Bank, City Bank, or Eastern Bank. If you qualify as a woman entrepreneur or innovative startup, prioritize TARA Uddokta, EBL Mukti/Startup, or Prime Bank’s 4%–5% refinance schemes. And if you need long-term project financing in a district or upazila town, compare Sonali Bank and Pubali Bank.