

Quick answer: A cold storage business loan in Bangladesh is term equipment/project financing or revolving working-capital credit offered by commercial banks, specialized agricultural banks, state-owned banks, and non-bank financial institutions (NBFIs) under Bangladesh Bank’s CMSME Master Circular (SMESPD Circular No. 01, 17 March 2025) and central bank SME/agro credit guidelines. Eligible potato, vegetable, fruit, fish/poultry, dairy, and seed cold-storage operators can borrow for compressors, chillers, insulated panels, pallet racks, backup generators, and seasonal operating expenses. Standard commercial bank rates generally sit around 12% to 14.5%, while qualifying small and medium enterprises under active central bank refinance windows (such as the Tk 25,000 crore CMSME refinance scheme or green/sector windows when active) can access lower capped rates where eligible. Reliable power/backup readiness, fire and environmental clearances, clean CIB records, and seasonal cash-flow planning are critical.
Updated 21 November 2026. Commercial bank interest rates, refinance fund allocations, refrigerant/environmental rules, and bank credit policies change periodically. Confirm current interest rates, limits, and permit checklists directly with your lender and regulatory authorities before applying.
In Bangladesh, seasonal harvests—especially potatoes in northern and western districts, vegetables and fruits in key growing belts, and fish, dairy, and poultry across regional hubs—can flood markets quickly and depress farm-gate prices if post-harvest storage is scarce. Cold storage facilities solve that bottleneck by extending shelf life, stabilizing supply across months, and protecting value for farmers, traders, and food processors. At the same time, running a cold storage business demands heavy upfront spending on refrigeration machinery, thermal insulation, and high-capacity electrical or generator power, followed by steady power and maintenance bills month after month. Knowing how banks structure loans for cold storage businesses helps operators match long-term cooling equipment to term credit and seasonal operating cash to revolving limits.
How Banks Evaluate Cold Storage Businesses in Bangladesh
Banks in Bangladesh evaluate cold storage enterprises within the CMSME framework under Bangladesh Bank’s CMSME Master Circular, alongside agriculture, SME, and commercial credit guidelines overseen by Bangladesh Bank’s SME & Special Programmes Department (SMESPD). Because post-harvest storage supports agriculture, food supply stability, and small/medium enterprise growth, compliant cold-storage operators with clear cash flow can receive constructive attention from SME, agro, and commercial lenders. You can see how enterprise categories work in our CMSME loan guide for Bangladesh.
Because a temperature failure or power outage can spoil stored goods fast, credit officers examine four specific operational risks in cold storage lending:
- Power reliability and backup capacity: Refrigeration runs continuously. Banks check whether your facility has a dependable grid connection and sufficient backup generator or power capacity to prevent costly temperature spikes during outages.
- Occupancy, storage fees, and seasonal turnover: Lenders look at expected chamber utilization across peak and off-peak months, storage rent/service fee rates, and whether you store third-party farmer/trader goods or buy and hold stock on your own account.
- Refrigerant, fire, and environmental compliance: Improper handling of refrigerants, pressure systems, or insulation materials creates safety and regulatory risks that banks check during site visits.
- Clean CIB status: The business entity as well as all owners, partners, directors, and guarantors must hold a clean Credit Information Bureau (CIB) record with no overdue or classified loan defaults.
Four Core Financing Facilities for Cold Storage
Cold storage operators typically need both multi-year equipment/facility funding and short-term operating liquidity. Pairing cooling machinery with a term loan and monthly electricity/payroll costs with a revolving line helps prevent cash mismatches.
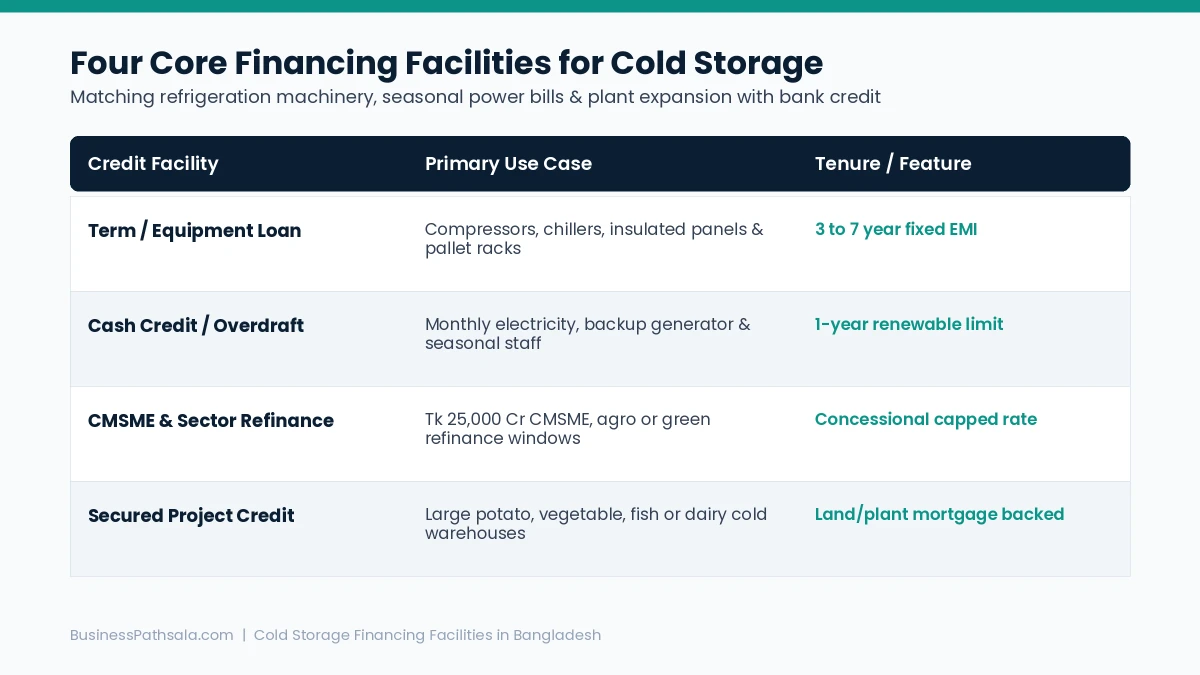
1. Term and Equipment Loans (For Chillers, Compressors, and Insulation)
Installing or upgrading refrigeration compressors, condensers, evaporators, insulated panels, cold-room doors, racking, or backup generators requires capital upfront. A term loan spreads repayment over roughly 3 to 7 years depending on asset life and bank policy, sometimes with a short installation or setup grace period where justified. Banks generally finance a share of vendor-quoted equipment or project costs while expecting owner equity contribution. For broader details on industrial and small-factory credit, see our small factory loan guide for Bangladesh.
2. Cash Credit (CC Hypothecation) and Overdraft (OD) for Operations
Revolving Cash Credit (CC Hypo) and Overdraft (OD) facilities help cover ongoing operating expenses—such as electricity/fuel bills, staff wages, routine maintenance, and seasonal stock/storage operations—when cash inflows and outflows do not line up evenly every week. Because these limits are typically reviewed annually and interest applies to the balance drawn, you can manage seasonal operating swings without paying interest on unused credit year-round.
3. Central Bank CMSME and Sector Refinance Windows
Eligible small and medium enterprises can ask participating banks and NBFIs whether active central bank refinance windows—such as the Tk 25,000 crore CMSME refinance scheme (where eligible customer rates are capped up to 7% per year when active) or specialized green/sector windows—apply to their cold-chain or storage upgrade. For related value-chain credit structures, see our agro-processing business loan guide for Bangladesh.
4. Secured Project and Commercial Credit for Larger Facilities
Larger cold storage chambers, multi-commodity storage hubs, or higher-limit facilities typically involve registered land/property mortgages or liquid security alongside hypothecation of cooling machinery and equipment.
Interest Rates and Real Repayment Math (BDT 15 Lakh Example)
Interest rates for cold storage loans depend on whether the facility uses an active central bank refinance window or follows standard commercial bank pricing. Outside subsidized refinance windows, commercial bank rates generally sit around 12% to 14.5% depending on credit risk, collateral, and market conditions. You can compare broader bank pricing in our guide to SME loan interest rates in Bangladesh.
To see how interest rate differences affect an equipment or cold-room upgrade loan, consider an illustrative BDT 15,00,000 (15 lakh) term loan repaid over 48 months (4 years) on a standard monthly reducing-balance schedule:
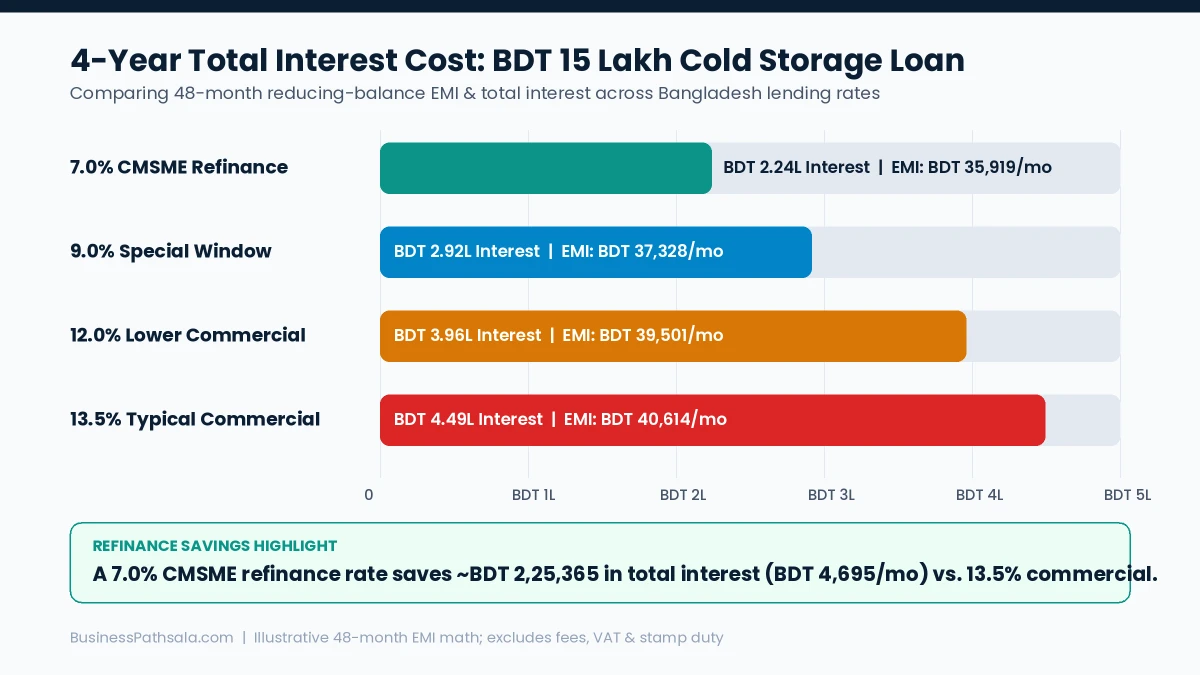
| Rate Scenario (BDT 15 Lakh, 48 Months) | Approx. Monthly EMI | Total Interest (4 Years) | Total Repayment |
|---|---|---|---|
| 7.0% Annual Rate (CMSME Refinance Window) | BDT 35,919 | BDT 2,24,130 | BDT 17,24,130 |
| 9.0% Annual Rate (Concessional / Special Window) | BDT 37,328 | BDT 2,91,723 | BDT 17,91,723 |
| 12.0% Annual Rate (Lower Commercial Tier) | BDT 39,501 | BDT 3,96,036 | BDT 18,96,036 |
| 13.5% Annual Rate (Typical Commercial Rate) | BDT 40,614 | BDT 4,49,495 | BDT 19,49,495 |
Illustrative calculation only: Figures assume equal monthly installments (EMI) without a grace period and exclude bank processing fees, CIB charges, stamp duties, valuation fees, and VAT. Actual repayment terms appear in your written sanction letter.
On a BDT 15 lakh loan over four years, a 7% refinance rate saves roughly BDT 4,695 per month and BDT 2,25,365 in total interest compared to a 13.5% commercial rate. Because cold storage power costs can rise in hot months, always test your monthly EMI against conservative net cash flow.
Banks and Institutions Financing Cold Storage in Bangladesh
Cold storage operators in Bangladesh borrow from scheduled commercial banks, specialized agricultural banks, state-owned banks, and NBFIs through their SME, Agro, and Commercial banking desks. Comparing institution types helps you pick a lender that fits your facility size and location.
| Lender Group | Examples of Active Institutions | Typical Strengths | Best Fit For |
|---|---|---|---|
| Private SME & Commercial Banks | BRAC Bank, City Bank, Eastern Bank (EBL), Prime Bank, Mutual Trust Bank (MTB), Dhaka Bank | Structured SME cash-flow evaluation, active refinance desks where eligible, and digital banking | Established cold-chain/storage operators (1–2+ years) with steady bank turnover |
| Specialized Agro Banks | Bangladesh Krishi Bank (BKB), RAKUB | Wide rural and upazila branch network near agricultural and post-harvest zones | Rural/regional cold storage and agro-linked storage operators |
| State-Owned Commercial Banks | Sonali Bank, Janata Bank, Agrani Bank, Rupali Bank | Broad district/upazila presence and multi-year project/commercial lending | Operators with collateral, regional footprint, or institutional ties |
| Shariah-Compliant Banks & NBFIs | Islami Bank Bangladesh, Shahjalal Islami Bank, Al-Arafah Islami Bank; IDLC, IPDC, LankaBangla | Islamic asset-backed/trade modes (such as Bai-Muajjal or HPSM) and equipment/lease options | Operators seeking Shariah-compliant modes or equipment financing |
Eligibility Criteria for Cold Storage Loans
While exact requirements depend on the lender, facility size, and security structure, most banks evaluate cold storage applicants against these core criteria:
- Operating Track Record: Many commercial banks look for at least 1 to 2 years of active operation with verifiable revenue and expense records before approving standard SME loans, while newer or larger greenfield projects often rely on sponsor equity, specialized agro/project windows, or property/FDR security.
- Age and Citizenship: Bangladeshi citizen with a valid National ID (NID), typically aged between 21 and 65 years at loan maturity.
- Clean CIB Status: The business entity and all owners, partners, directors, and personal guarantors must have a clean Credit Information Bureau (CIB) record with no overdue or classified defaults.
- Viable Margin and Power Readiness: Clear net margins after electricity/fuel, staff, maintenance, and storage costs, supported by dependable power and safety arrangements.
- Collateral and Guarantees: Smaller loans for established units may rely on personal guarantors, machinery/stock hypothecation, and security cheques, whereas larger term loans or higher limits generally require registered property collateral or liquid security.
Required Documents and Permits Checklist
Cold storage facilities face fire, environmental, and premises checks alongside standard banking paperwork. Gather these six document categories where applicable before applying:
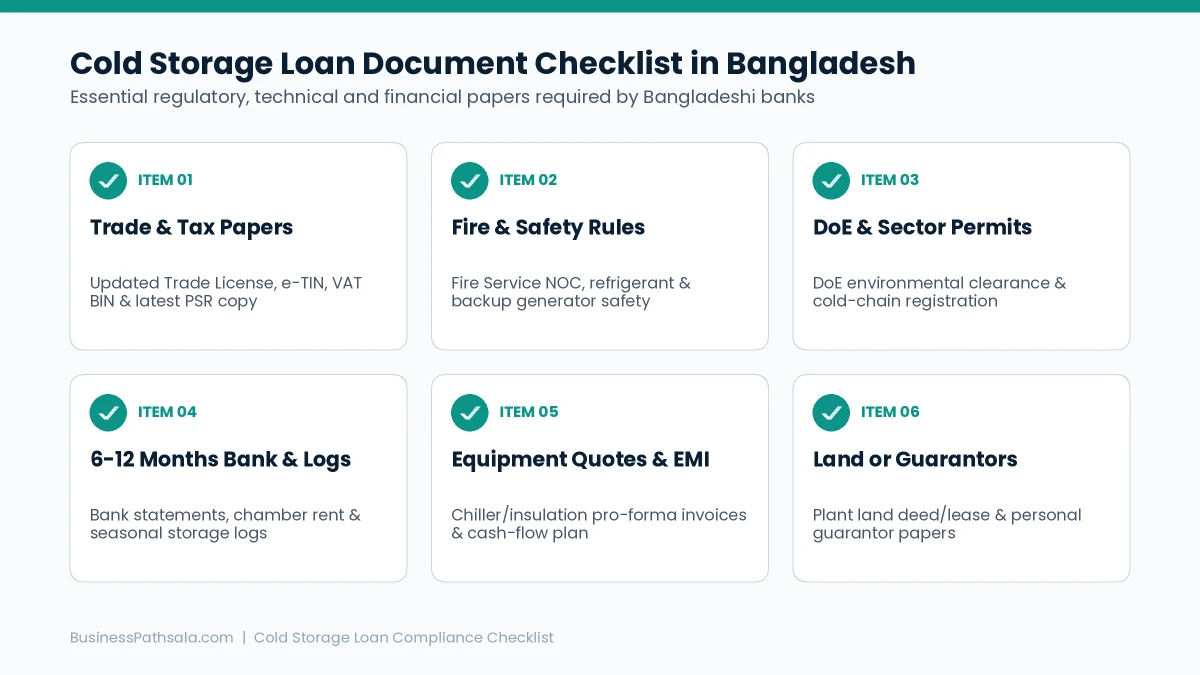
- Trade License and Tax Records: Updated Trade License for cold storage/warehousing/agro-storage; valid NID and passport photos of owner/partners/directors; active e-TIN certificate; latest income tax return acknowledgement (PSR); and VAT/BIN or RJSC/partnership papers where applicable.
- Fire and Operational Safety Compliance: Valid license from the Bangladesh Fire Service and Civil Defence, along with electrical/generator and refrigerant/pressure safety compliance where applicable.
- Environmental and Industry Registration: Environmental clearance from the Department of Environment (DoE) where required, plus BFSA or BSTI (if storing/handling regulated food products) and BSCIC or DIFE registration where applicable.
- Bank Statements and Storage/Power Records: Last 6 to 12 months of business bank statements, supported by storage receipts/client ledgers, electricity/generator fuel bills, and revenue logs.
- Project Profile and Equipment Quotations: A practical summary of your cooling equipment or chamber plan, dated vendor quotations, operating cost estimates (especially electricity), and monthly repayment schedule. Use our guides on preparing an SME loan project profile in Bangladesh and writing a business plan for a bank loan.
- Premises and Guarantor/Security Papers: Land title deeds, mutation (Namjari), and tax receipts (or commercial lease agreement), plus NID, photos, and income/business details of guarantors (or collateral papers if secured).
Step-by-Step: How to Apply for a Cold Storage Business Loan
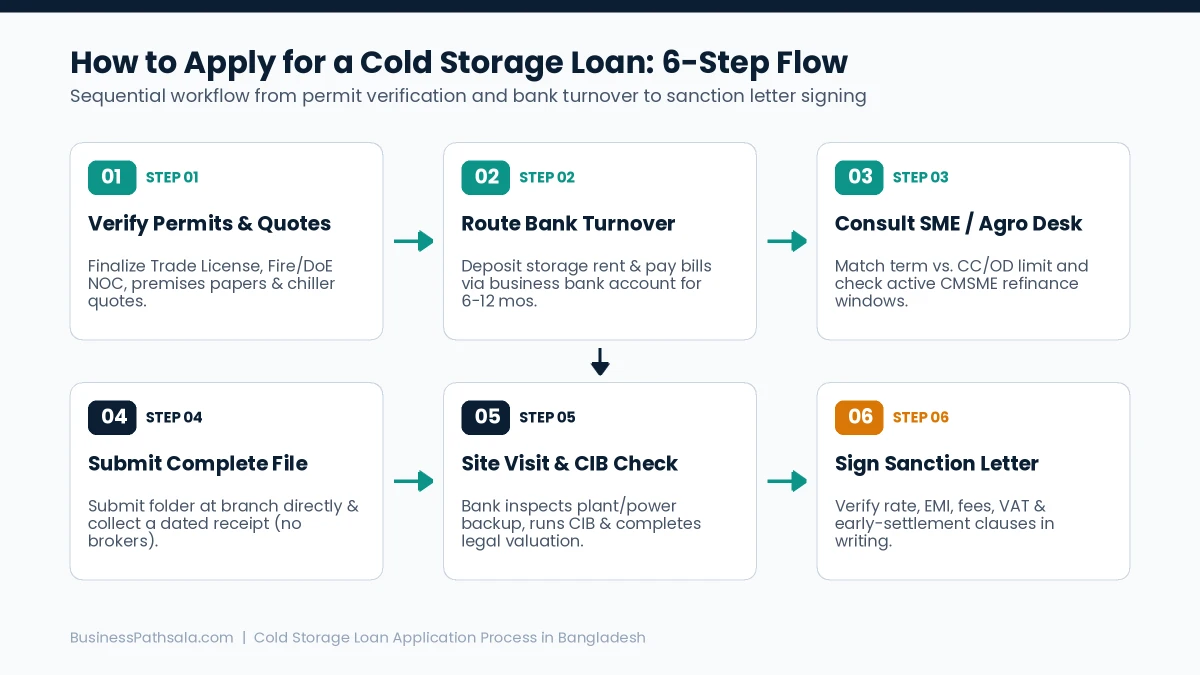
- Verify permits, power/safety setup, and equipment quotes. Ensure your Trade License, Fire Service and DoE clearances, premises papers, and vendor quotations are current and complete.
- Route storage collections and operating expenses through a bank account. Depositing revenue regularly into your business bank account over 6 to 12 months gives credit officers verifiable cash-flow proof.
- Speak with the branch SME, Agro, or Commercial desk. Ask which term-loan or working-capital facility fits your cold storage capacity, whether any refinance window applies, and what exact document checklist they require.
- Submit a complete application and keep an acknowledgement. Hand in your filled form and supporting folder at the branch and collect a dated receipt. Avoid paying unofficial middlemen promising guaranteed approval.
- Support site inspection, CIB check, and legal/valuation review. Expect a bank officer to inspect the cold room/plant, power backup, safety compliance, and records while head office runs CIB checks and any required valuation or legal vetting.
- Verify written terms on the sanction letter before signing. Check the interest rate, EMI or revolving limit terms, processing fee, VAT, guarantor/collateral clauses, and early-settlement rules in writing.
Common Mistakes Cold Storage Operators Make When Borrowing
- Underestimating electricity and backup power costs: High power bills in warmer months can squeeze net cash flow if not built into your repayment budget.
- Keeping storage income outside bank statements: Unrecorded cash makes revenue harder to verify and often reduces approved credit limits.
- Using short-term working capital to fund long-term cooling assets: Mismatching asset life with short-term debt can strain liquidity before cooling upgrades pay off.
- Overlooking fire, environmental, or land/lease paperwork: Missing regulatory or premises documents can delay approval or disbursement.
If you are also exploring broader small-business or entrepreneur financing routes in Bangladesh, you can explore our Uddokta loan guide for Bangladesh.
Frequently Asked Questions
Can I get a bank loan to set up a new cold storage unit in Bangladesh?
Getting an unsecured bank loan for a brand-new cold storage setup with no operating history is difficult because many banks look for 1 to 2 years of active business track record. New operators typically start with sponsor equity, specialized agro/project windows where eligible, or collateral/FDR-backed financing before qualifying for standard bank SME facilities.
What is the interest rate on a cold storage business loan in Bangladesh?
Standard commercial bank loans for cold storage generally range around 12% to 14.5% depending on the bank, credit risk, and collateral. Eligible small and medium enterprises under active central bank refinance windows (such as the Tk 25,000 crore CMSME refinance scheme or specialized sector/green windows when active) can access lower capped rates where eligible.
Which loan format is better for cold storage: Term Loan or CC/OD?
A term loan is better for compressors, chillers, insulation, racking, or facility upgrades repaid over a multi-year EMI schedule, while a revolving Cash Credit (CC) or Overdraft facility is better for ongoing electricity/power costs, wages, and seasonal operating expenses.
Is land collateral required for a cold storage business loan?
Smaller SME facilities for established operators may rely on personal guarantors, machinery/stock hypothecation, and security cheques depending on bank policy, while larger term loans or project facilities generally require registered land/property collateral or liquid security.
How long does cold storage loan approval take in Bangladesh?
Timelines depend on loan size, collateral, and verification steps. Straightforward working-capital or existing-client files with complete documents and clean CIB checks can take a few weeks, while larger term loans involving property valuation, legal vetting, or refinance processing can take longer.
Official Sources and Further Reading
- Bangladesh Bank SMESPD Circular No. 01 — CMSME Financing Master Circular (17 March 2025): Official CMSME definitions, credit guidelines, and lending rules in Bangladesh.
- Bangladesh Bank SME & Special Programmes Department (SMESPD): Central bank refinance windows and SME credit directives.
- Bangladesh Fire Service and Civil Defence: Fire safety licensing and commercial/industrial safety compliance in Bangladesh.
- Department of Environment (DoE): Environmental clearance guidelines for storage and processing facilities.
Final Takeaway
Securing a cold storage business loan in Bangladesh comes down to matching cooling equipment and chamber upgrades with term credit, funding power and seasonal operating needs with revolving working capital, keeping fire, environmental, and premises compliance in order, and maintaining clean bank statements and CIB records. Compare two or three lenders and verify all terms in writing before signing.
Financial information notice: This article is for general educational purposes only and does not constitute a loan offer, financial advice, or a guarantee of loan approval. Bank interest rates, refinance schemes, collateral rules, and regulatory licensing requirements may change over time. Always verify current terms directly with Bangladesh Bank, relevant regulatory authorities, and your chosen bank or financial institution.


